
Blogs
Worldwide Epilepsy Monitoring Unit Market Hits $642.7M in 2025, Forecasted to Reach $979.23M by 2032 at 6.22% CAGR
By pmarketresearch, 2026-09-16
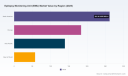
Strategic Intelligence for the Next Wave: Inside the Global Epilepsy Monitoring Unit Market Outlook
The landscape of neurological care is shifting rapidly, and nowhere is this transformation more critical than within Epilepsy Monitoring Units (EMUs). As healthcare systems worldwide grapple with rising seizure disorder prevalence, evolving accreditation standards, and the integration of advanced neurodiagnostic technologies, strategic clarity is no longer optional—it is imperative. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Epilepsy Monitoring Unit (EMU) Market report, designed to equip decision-makers with the actionable intelligence needed to navigate the complexities of 2026 and beyond.
This research is not merely a retrospective analysis. It is a forward-looking strategic tool calibrated to inform capital allocation, product development, market entry, and partnership strategies in a sector defined by both technological disruption and stringent regulatory frameworks. By synthesizing historical performance with rigorous forecasting, this report provides a clear line of sight into where value will be created and captured over the next seven years.
Market Trajectory and Growth Fundamentals
Understanding the momentum of the EMU market requires a clear view of its historical foundation and projected expansion. Between 2020 and 2025, the global market demonstrated resilience and steady growth, rising from approximately 490.15 million USD to an estimated 642.7 million USD. This trajectory reflects sustained investment in specialized neurological infrastructure and the increasing clinical reliance on long-term video-EEG telemetry for accurate seizure classification and surgical candidacy assessment.
Looking ahead, the forecast period from 2026 through 2032 signals continued expansion, with the market projected to reach nearly 979.23 million USD by the end of the forecast window. This growth is underpinned by a compound annual growth rate (CAGR) of 6.22 percent, a figure that underscores the market's structural attractiveness while also highlighting the competitive intensity that comes with such expansion. For executives planning product lifecycles or facility investments, this growth curve offers a quantitative anchor for scenario planning and demand forecasting.
Importantly, the market's evolution is not uniform. The interplay between hardware deployment, software analytics adoption, and consumable cycles creates distinct value pools that require differentiated strategic approaches. Our analysis dissects these dynamics without losing sight of the overarching market engine, ensuring that stakeholders can align their initiatives with the most promising avenues of revenue generation.
Report Architecture: What Decision-Makers Will Find Inside
A market research report is only as valuable as its operational relevance. The PW Consulting Worldwide EMU Market study is structured to move beyond high-level summaries and deliver granular, decision-ready content across multiple dimensions. The report is organized to support a range of strategic use cases, from M&A target screening to regional launch prioritization and competitive positioning.
At its core, the publication provides a multi-layered segmentation analysis that breaks down the market by region, product type, and end-user category. This structure allows readers to assess where growth is concentrated, how demand patterns differ across care settings, and which product categories are driving incremental expansion. Rather than presenting static snapshots, the analysis traces evolutionary paths within each segment, identifying shifts in purchasing behavior, clinical adoption curves, and technology substitution trends.
The research also incorporates a detailed examination of market concentration dynamics. With a CR3 of 48.35 percent and a CR5 of 62.1 percent, the EMU market exhibits a moderately concentrated competitive structure. This has meaningful implications for pricing power, innovation velocity, and partnership strategies. The report explores how incumbent players defend share, how challengers differentiate, and where whitespace opportunities may exist for new entrants or specialized solution providers.
Beyond segmentation and concentration, the study integrates a robust competitive profiling section. Each major player is evaluated through the lens of product architecture, clinical workflow alignment, geographic footprint, and recent strategic developments. These profiles are not descriptive catalogs; they are analytical assessments designed to reveal strengths, vulnerabilities, and potential moves in the next planning cycle.
Worldwide High-density Electroencephalography (HD EEG) Market
To ensure practical applicability, the report includes:
- Historical market sizing and forecast modeling with transparent methodological assumptions
- Segment-level growth drivers and restraining factors that shape near-term commercial outcomes
- Regulatory and accreditation developments that influence facility design and service delivery models
- Reimbursement and coding considerations that affect patient access and hospital economics
- Technology adoption patterns, including wireless monitoring, remote assessment tools, and wearable adjuncts
- Staffing and operational benchmarks that inform capacity planning and service configuration
By weaving together clinical, regulatory, economic, and technological threads, the report enables stakeholders to construct a unified view of the EMU ecosystem and its future direction.
Competitive Landscape: Leaders, Differentiators, and Emerging Moves
The EMU market is shaped by a set of established neurodiagnostic and medical technology companies, each bringing distinct capabilities to the monitoring environment. Natus Medical Incorporated, headquartered in Pleasanton, California, has built a reputation around wireless long-term monitoring solutions such as the Natus EMU40EX Wireless LTM Amplifier. Its emphasis on patient mobility during extended monitoring sessions aligns with the clinical priority of capturing realistic seizure patterns without confining patients to rigid setups.
Cadwell Industries, based in Kennewick, Washington, offers the Arc EEG portfolio, including Arc Zenith for high-channel-count EMU monitoring and Arc Apollo+ for flexible in-hospital epilepsy monitoring with video integration. The company's focus on scalable channel configurations and intracranial monitoring support positions it for complex diagnostic workflows where precision and adaptability are paramount.
Nihon Kohden Corporation, headquartered in Tokyo, Japan, continues to expand its wireless and wired EEG systems optimized for EMU, ICU, and broader neurological monitoring contexts. Its December 2025 introduction of advanced EEG technology and a second-generation Live View Panel Pro reflects a strategic push toward enhanced remote neurophysiological assessment, a capability that increasingly intersects with off-site monitoring models and multidisciplinary care coordination.
Compumedics Limited, based in Melbourne, Australia, contributes to the market through its neurodiagnostic and EEG monitoring equipment, integrated within a wider sleep and neurological diagnostics portfolio. Its presence underscores the overlap between epilepsy monitoring and adjacent clinical domains, suggesting potential cross-selling and platform integration opportunities.
Medtronic plc, with headquarters in Dublin, Ireland, brings a broader neuromodulation and monitoring perspective to the EMU environment. While its footprint extends well beyond epilepsy monitoring alone, its involvement in long-term epilepsy evaluation workflows and therapeutic technologies gives it a strategic vantage point on integrated care pathways that bridge diagnosis and intervention.
Koninklijke Philips N.V., based in Amsterdam, Netherlands, contributes patient monitoring and EEG-related solutions within its neurology and critical care portfolio. Its scale and system-integration capabilities make it a relevant player for institutions seeking to embed EMU functions within wider hospital monitoring architectures.
Empatica Inc., operating across Milan, Italy, and Boston, Massachusetts, represents a different vector of innovation. Its wearable seizure monitoring systems, such as Embrace, focus on physiological signal-based detection that can complement traditional video-EEG setups. This wearable adjunct approach is strategically significant because it points toward hybrid monitoring models, remote triage, and post-discharge surveillance scenarios that may expand the effective footprint of epilepsy care.
These companies are not operating in a static environment. Recent developments illustrate the pace of change: the opening of new EMU facilities, product advancements in remote assessment, and accreditation updates that reshape service delivery expectations. Each of these events carries implications for demand, competitive positioning, and infrastructure planning.
Market Dynamics: Regulation, Reimbursement, and Operational Realities
Strategic planning in the EMU sector must account for a web of operational and policy-driven factors that influence both supply and demand. Regulatory and accreditation frameworks play a defining role. NAEC-accredited epilepsy centers are expected to maintain EMUs supported by multidisciplinary teams, pharmacological services, and safety protocols suited to long-term video-EEG telemetry. These requirements raise the barrier to entry for low-resource setups and reinforce the advantage of organizations that can deliver comprehensive, protocol-driven care.
The 2026 accreditation process updates add a particularly important nuance. They clarify that 24/7/365 EMU monitoring may be provided by off-site third parties, a shift that opens new service delivery models and could alter how centers configure monitoring capacity. For technology providers and service organizations, this development creates possibilities for remote monitoring partnerships, centralized reading services, and hybrid staffing arrangements. For hospitals, it introduces both efficiency opportunities and governance considerations.
Safety standards further shape the operational environment. EMU practices commonly include constant video-EEG monitoring by technicians, padded side rails, audible alarms, and immediate staff response protocols designed to manage provoked seizures and reduce complications such as status epilepticus. These standards are not merely clinical best practices; they influence equipment specifications, staffing models, and facility design, all of which have cost and capacity implications.
Reimbursement dynamics add another layer of complexity. Many EMU patients begin their stay under Observation Status per insurance policies, which can result in higher patient copayments for video EEG monitoring billed under APCs rather than being bundled into a DRG. Such coding and billing distinctions affect hospital economics, patient affordability, and the financial planning of epilepsy programs. Understanding how these reimbursement pathways interact with service volume and monitoring duration is essential for forecasting realistic revenue outcomes.
Labor and staffing realities complete the operational picture. EMU staffing models vary across centers, but dedicated teams of epilepsy specialists, EEG technologists, and nurses are generally required for continuous monitoring and rapid intervention during seizure events. As facilities expand capacity or adopt new monitoring technologies, workforce availability, training requirements, and shift coverage become critical constraints. These factors can influence the pace of EMU expansion and the attractiveness of solutions that reduce manual burden or improve remote oversight.
Worldwide Epilepsy Monitoring Unit (EMU) Market
Why This Research Matters for 2026 Decision-Making
The 2026 outlook is a pivotal moment for EMU market stakeholders. Growth is projected to continue, but the path of that growth will be shaped by technology adoption, accreditation flexibility, reimbursement behavior, and the competitive responses of leading firms. In this environment, generalized market narratives are insufficient. Decision-makers need specific, structured intelligence that connects macro trends to operational choices.
This report is designed to serve that need. It gives executives a framework for evaluating where to invest, what capabilities to prioritize, and how to interpret competitor movements with greater confidence. Whether the goal is to expand into new geographic markets, refine a product roadmap, assess partnership opportunities, or anticipate the impact of accreditation and reimbursement changes, the study provides a grounded basis for strategic judgment.
The analysis also helps organizations avoid common pitfalls. In a market with moderate concentration and strong clinical standards, assumptions about rapid commoditization or uniform adoption can be misleading. Similarly, overlooking the operational significance of staffing, safety protocols, and off-site monitoring options can lead to misaligned plans. By addressing these variables explicitly, the report helps teams build strategies that are resilient to both regulatory shifts and competitive surprises.
Positioning for the Forecast Period
As the market moves from 2026 toward 2032, the organizations that succeed will be those that combine clinical credibility with operational agility. Hardware performance, software analytics, consumable economics, and service models will all matter, but their relative importance will differ across end-user types and regional contexts. Specialized epilepsy centers, general hospitals and clinics, and academic or research institutes each present distinct demand drivers and procurement logics, and the report reflects these differences in its segmentation analysis.
The presence of both established device manufacturers and emerging wearable or software-centric innovators suggests that the competitive field will continue to evolve. Traditional EMU vendors may increasingly need to address remote assessment, data integration, and workflow efficiency, while newer solution providers will need to demonstrate clinical reliability and compatibility with existing monitoring standards. In this setting, strategic positioning will depend on a clear understanding of where each company creates value and where gaps remain.
This is precisely the kind of understanding that the PW Consulting Worldwide EMU Market report is built to provide. It offers a comprehensive yet actionable view of market size, growth rhythm, competitive structure, and the operational forces that will shape purchasing and deployment decisions.
Next Steps for Strategic Teams
For organizations preparing budgets, product plans, or market-entry assessments for 2026, the full report delivers the depth required to move from intuition to evidence-based strategy. The macro trajectory, segment dynamics, competitive profiles, and regulatory context discussed here are intended as a preview of the broader analytical framework available in the complete publication.
To access the full market sizing, segmentation detail, competitive assessments, and forecast models, we invite you to explore the complete Worldwide Epilepsy Monitoring Unit (EMU) Market research on the PW Consulting platform. The full study is designed to support leadership teams that need more than summary figures—they need a strategic map for the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Epilepsy Monitoring Unit (EMU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide K12 Art Course Market Hits $22.64B in 2025, Set for 8.52% CAGR Through 2032
By pmarketresearch, 2026-09-16
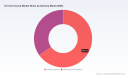
Navigating the Global K12 Art Course Market: Strategic Imperatives for 2026 and Beyond
The landscape of K12 education is undergoing a profound transformation, with arts education emerging as a critical battleground for edtech providers, curriculum publishers, and school districts alike. As stakeholders prepare their strategies for 2026, the Worldwide K12 Art Course Market stands out not merely as a niche segment but as a bellwether for broader pedagogical shifts toward creativity, digital proficiency, and holistic student development. Our latest market research offers a comprehensive lens into this evolving ecosystem, providing the granular intelligence necessary for informed decision-making in an increasingly complex environment.
Market Trajectory and Growth Dynamics
Understanding the trajectory of the K12 art course market requires a clear view of its historical momentum and future velocity. Based on an extensive analysis anchored in 2025 and projecting through 2032, the market demonstrates a robust upward trend that underscores its strategic relevance. The global revenue generated by K12 art courses is projected to accelerate significantly over the forecast period, reflecting a compound annual growth rate that signals sustained investor and institutional confidence.
This growth is not linear but is driven by converging factors including the digitalization of learning materials, heightened emphasis on STEM-to-STEAM transitions, and the post-pandemic normalization of hybrid delivery models. For enterprise strategists, this macro trajectory offers a foundational baseline against which to calibrate expansion plans, partnership opportunities, and product roadmaps. The sheer scale of the market in dollar terms, combined with the consistent growth velocity, points to a mature yet dynamic sector where early movers and agile innovators can capture disproportionate value.
The Digital and Hybrid Inflection Point
The integration of digital and media arts into K12 curricula represents a pivotal shift that is redefining market boundaries. Traditional visual arts and music programs are increasingly complemented—and in some cases supplanted—by courses that leverage creative software, digital storytelling, and multimedia production. This shift is not merely a pedagogical preference but a structural change in how education providers deliver value. Platforms that enable digital art creation are finding fertile ground in schools worldwide, driven by the need to equip students with skills relevant to a technology-centric economy.
Simultaneously, the delivery mode landscape is bifurcating yet converging. While in-person learning retains a dominant share of the market due to the inherent tactile and collaborative nature of art education, online and hybrid learning models are gaining substantial traction. This dual-channel growth creates strategic complexity: vendors must decide whether to optimize for physical classroom integration, virtual delivery, or a seamless hybrid experience that bridges both. Our research dissects these dynamics to reveal where the most resilient revenue streams are forming.
Regulatory and Privacy Frameworks Shaping Deployment
Strategic planning in the K12 art course market cannot ignore the regulatory architecture that governs data usage and student privacy. Recent updates to frameworks such as COPPA have clarified that schools may consent on behalf of parents only when data use is strictly for educational purposes, prohibiting targeted advertising or commercial disclosure in K12 edtech environments. Platforms offering art software or online courses must ensure their data practices align with these constraints to maintain compliance and trust.
In parallel, FERPA protections extend to education records generated within digital art platforms, limiting disclosure without consent and imposing obligations on third-party vendors acting on behalf of schools. For companies deploying creative tools or hosting student artwork online, these regulations are not mere legal checkboxes but operational guardrails that influence product design, vendor agreements, and market entry strategies. Ignoring these nuances can result in significant compliance risks, while proactive alignment can serve as a competitive differentiator.
Competitive Landscape: Established Players and Emerging Models
The competitive ecosystem in K12 art education is characterized by a diverse array of players, ranging from full-service online curriculum providers to specialized software vendors and independent marketplace instructors. A market with a relatively fragmented concentration profile suggests that no single entity dominates the field, creating opportunities for both collaboration and disruption. Our research provides deep profiles of key companies, examining their strategic positioning, product offerings, and recent moves that signal their trajectory in this space.
Worldwide K12 Tutoring Market
Curriculum and Platform Leaders
Stride Inc and Connections Academy represent the leading edge of online K12 curriculum providers with dedicated arts components. Stride offers a comprehensive suite that includes courses such as Summit Fine Art and Art in World Cultures, complemented by annual student art competitions that reinforce brand engagement and student participation. Their recent launch of a major annual competition highlights a strategy of community building and creative showcase as a retention and reputation tool. Connections Academy, backed by Pearson global resources, integrates arts education into virtual classroom technology and electives, leveraging the scale of a tuition-free online public school model to reach broad audiences.
Savvas Learning Company continues to deliver curriculum materials and digital platforms with arts integration options, including partnerships that support assessment and content delivery. Their evolution from Pearson K12 underscores the industry's shift toward modular, platform-enabled delivery where arts content can be bundled with core academic tracking. Meanwhile, Hillsdale College K12 provides a distinct value proposition with free or low-cost classical curriculum emphasizing fine arts and humanities, appealing to segments that prioritize content-rich, balanced programs.
Technology Enablers and Marketplace Innovators
Adobe Inc operates as a critical enabler in this ecosystem, supplying creative software tools tailored for K12 art education. Their tools enable digital art creation and curriculum integration across schools worldwide, effectively serving as infrastructure for digital and media arts courses. As the market grows, the interplay between curriculum providers and software vendors becomes increasingly strategic, with integration depth influencing adoption.
Outschool has carved a unique niche by offering live online classes for ages 3 to 18, including numerous K12 art and creative courses taught by independent instructors. This marketplace model introduces flexibility and supplemental education options that complement formal school offerings. Artsonia, as the world's largest student art museum platform, hosts K12 student artwork and enables global sharing, exhibitions, and curriculum support. This platform not only serves as a showcase but also as a pedagogical tool for art teachers, illustrating how community and visibility can drive engagement.
Worldwide K12 Art Course Market
Recent Moves and Partnership Signals
Recent developments provide real-time signals of how the competitive landscape is evolving. In early 2026, Renaissance Learning rolled out an integration of a major math curriculum into its assessment platform, building on prior partnerships that support broader K12 core curriculum including potential arts-aligned data tracking. Such integrations suggest a trend toward consolidated platforms where arts data can be tracked alongside academic metrics, enhancing the value proposition for districts seeking holistic student insights.
On the institutional front, Chicago Public Schools unveiled a districtwide arts education plan establishing a unified pre-K12 arts curriculum and a data-driven system to track instruction quality. This kind of district-level commitment signals growing demand for structured, measurable arts programs that align with broader educational goals, creating procurement and partnership opportunities for vendors that can support systematic implementation.
Operational and Strategic Insights Within the Report
Beyond market sizing and competitive profiling, our research is designed to equip decision-makers with actionable frameworks. The report delves into course type segmentation to illuminate where demand is strongest and how content strategies should be calibrated. We examine the nuances between visual arts, music and performing arts, and digital and media arts, identifying the growth vectors within each category without relying on simplistic aggregates.
-
Detailed analysis of delivery mode preferences across different institutional types, highlighting the interplay between in-person and online/hybrid models and how blended approaches are shaping procurement decisions.
-
Regional demand patterns and localization factors that influence curriculum adoption, considering cultural preferences, infrastructure readiness, and regulatory environments.
-
Competitive benchmarking across company types, from full-curriculum providers to software vendors and independent instructor networks, identifying gaps and whitespace opportunities.
-
Regulatory impact assessments that translate privacy and data protection requirements into operational guidance for platform design, vendor management, and market entry.
-
Labor and delivery cost considerations, recognizing that K12 art education relies heavily on specialized human labor for curriculum delivery and that online platforms supplement rather than replace certified educators.
These insights are structured to support scenario planning, investment allocation, and partnership strategy. Readers will gain a clear understanding of where value is being created, which business models are proving resilient, and how macro trends such as digitalization and regulatory evolution are reshaping the rules of competition.
Strategic Imperatives for 2026 Decision-Making
As the market advances toward its projected growth targets, enterprises across the value chain must make deliberate choices about positioning and resource allocation. The data suggests that growth will be sustained by the ongoing digital transformation of arts education, the integration of creative tools into broader curricula, and the expansion of hybrid delivery options that meet diverse learner needs. However, realizing this potential requires navigating a complex terrain of regulatory compliance, competitive fragmentation, and evolving pedagogical expectations.
For curriculum providers, the imperative is to deepen arts integration while ensuring that digital components are pedagogically sound and compliant with student privacy standards. For technology vendors, the opportunity lies in creating tools that seamlessly fit into classroom workflows and support the creative process without creating data exposure risks. For marketplace and community platforms, scale and quality assurance remain critical challenges, as does the ability to demonstrate educational value to schools and parents.
Furthermore, the labor dimension of art education delivery cannot be overlooked. While platforms can enhance reach and efficiency, certified art educators and instructors remain central to effective curriculum delivery. Strategies that leverage technology to augment rather than replace human expertise are likely to gain greater acceptance and sustain long-term success. Our research provides the evidence base to inform these strategic judgments, offering a clear view of where investment yields the highest returns and where missteps carry the greatest risk.
Access the Full Intelligence
The Worldwide K12 Art Course Market is at an inflection point where strategic clarity can translate directly into competitive advantage. The insights summarized here represent only a fraction of the depth available in our full report. To access detailed market sizing, forward projections, company profiles, regulatory analyses, and actionable recommendations tailored to your strategic needs, we invite you to explore the complete research on our website. This intelligence is designed to serve as a trusted reference for boards, strategy teams, product leaders, and investors seeking to navigate this dynamic market with confidence.
Discover the full scope of opportunities, the competitive moves that are reshaping the landscape, and the data-driven guidance that can inform your 2026 strategy. The future of K12 art education is being written now, and the organizations that act on comprehensive intelligence will be best positioned to lead.
For detailed analysis of this topic, please visit the official page: Worldwide K12 Art Course Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Double Membrane Biogas Holder Market Hits $241.4M in 2025, Projects 6.24% CAGR to 2032
By pmarketresearch, 2026-09-16
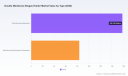
Strategic Intelligence: Navigating the Worldwide Double Membrane Biogas Holder Market 2026–2032
The global transition toward renewable energy and circular economy principles has placed anaerobic digestion at the forefront of sustainable infrastructure development. Central to the efficiency and safety of these systems lies the double membrane biogas holder—a critical component designed to manage gas pressure, contain odors, and optimize storage capacity. As industrial and municipal operators seek reliable, low-maintenance solutions, the Worldwide Double Membrane Biogas Holder Market is experiencing a structural shift driven by technological maturation and regulatory compliance demands.
PW Consulting is proud to release our latest comprehensive market research, tailored to equip stakeholders with the actionable intelligence required for strategic decision-making in 2026 and beyond. This report moves beyond surface-level estimates, offering a granular analysis of market dynamics, competitive positioning, and technological trends that define the sector through 2032.
Market Trajectory and Growth Outlook
The double membrane biogas holder sector has demonstrated resilience and consistent expansion over the past half-decade. From 2020 to 2025, the market evolved from a niche industrial component to a mainstream element in renewable energy infrastructure. Historical data indicates a steady revenue progression, with the market size reaching significant milestones as adoption rates accelerated across agricultural and wastewater treatment sectors.
Looking forward, the forecast period from 2026 to 2032 projects continued growth, supported by the global push for methane capture and biogas upgrading. The market is expected to expand at a Compound Annual Growth Rate (CAGR) of 6.24% during this forecast window. This trajectory suggests that revenue will surpass previous records by 2032, reflecting increased capital expenditure in green infrastructure projects. For investors and manufacturers, understanding the velocity of this growth is essential for capacity planning and market entry strategies. The base year 2025 serves as a robust foundation for these projections, capturing the post-pandemic recovery and the subsequent surge in environmental, social, and governance (ESG) driven investments.
Key Growth Drivers
Several macroeconomic and technical factors are converging to sustain this upward trend. First, the intermittent nature of renewable energy sources necessitates flexible storage solutions that can buffer production and consumption cycles. Double membrane holders offer this flexibility with lower installation costs compared to rigid steel alternatives. Second, stringent environmental regulations regarding odor control and methane permeation are compelling operators to upgrade aging infrastructure with high-performance membrane systems. Third, the integration of biogas plants with existing wastewater treatment facilities is creating hybrid demand streams, particularly in regions focusing on water-energy nexus solutions.
Regional and Segment Analysis
Our research provides a detailed breakdown of performance across key global regions. Europe continues to hold a predominant share of market revenue, reflecting its mature biogas industry and early adoption of anaerobic digestion technologies. However, the dynamics are shifting. Asia Pacific is emerging as a high-potential region, driven by aggressive waste-to-energy policies and rapid industrialization. North America maintains a stable presence, largely influenced by municipal sewage treatment upgrades and industrial wastewater mandates. Meanwhile, Latin America and the Middle East and Africa represent developing markets where infrastructure investment is beginning to unlock new opportunities for storage solution providers.
Segmentation by product type reveals distinct preferences between Tank-Mounted Gasholders and Slab-Mounted/Independent Gasholders. The choice between these configurations often depends on site constraints, existing infrastructure, and specific operational pressures. Tank-mounted solutions are frequently favored for their integration capability with existing digesters, while independent units offer flexibility for brownfield sites or expansions. Our analysis details the adoption rates and strategic advantages of each type without exposing the sensitive revenue splits that could compromise competitive advantage prior to full report access.
Application Landscape
The versatility of double membrane technology allows it to serve diverse application verticals. Agricultural biogas plants remain a primary consumer, leveraging these systems to manage gas production from organic waste and energy crops. Industrial wastewater treatment represents another significant segment, where consistent gas capture is necessary to meet emission standards and recover energy. Municipal sewage treatment facilities are increasingly integrating double membrane holders to handle variable gas flows efficiently. Additionally, landfill gas projects continue to utilize this technology for gas flaring prevention and energy recovery. Each application presents unique technical requirements regarding pressure regulation, material durability, and sizing, which our report dissects thoroughly.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of specialized membrane manufacturers, engineering firms, and integrated solution providers. With a CR3 of approximately 31.45% and a CR5 of 48.2%, the market is moderately fragmented, allowing room for specialized players to compete on technology and service quality rather than price alone.
Leading producers such as CENO-TEC, formerly known as Sattler AG and AGROTEL, remain pivotal in the supply chain. Based in Austria, CENO-TEC specializes in high-quality PVC-coated technical fabrics, providing the essential inner and outer membranes for flexible, low-pressure storage systems. Their over 30 years of experience in biogas applications set a benchmark for material performance. Similarly, WesTech Engineering in the USA supplies the DuoSphere™ double membrane gas holders, offering lightweight PVC-coated polyester structures that reduce installation time and cost compared to steel alternatives.
In China, the landscape is vibrant with manufacturers like YHR Tanks and Chengdu AMOCO Architecture Technology Co., Ltd. YHR Tanks offers customizable double membrane biogas holders integrated with glass-fused-to-steel tanks, providing end-to-end design and installation services. Chengdu AMOCO, with over 23 years of experience, has installed more than 1500 units across 30 countries. Their recent activities highlight their expansion momentum, including the completion of a 1500 m³ installation in Guangxi, China, and the initiation of a 4400 m³ unit in Thailand as of January 2026. Further expanding their footprint, AMOCO completed a significant installation in Araucanía, Chile, in late 2025 and executed a membrane replacement project in Indonesia, demonstrating lifecycle support capabilities.
Other key players include Sichuan Mondes Green Technology Co., Ltd., positioned as a leading supplier in China for dual membrane gas domes, and Industrial & Environmental Concepts, Inc. (IEC) in the USA, which offers ISO-certified, chemically-resistant membranes for all biogas system types. European expertise is represented by Baur Folien GmbH in Germany and Membrane Systems Europe in the Netherlands, the latter specializing in frequency-welded membranes up to 40m diameter.
Worldwide Double Membrane Biogas Holder Market
In the UK market, Utile Engineering serves as the exclusive supplier and installer of CENO-TEC gas holders since 1991, ensuring localized support for reliable storage solutions. Biogas Products Ltd supplies stand-alone holders with UK-manufactured membranes, available in sizes up to 30,000 m³ in various geometries for biogas and hydrogen storage. Veolia, through its TECON brand, provides custom-made double membrane gasholders for wastewater treatment and industrial applications globally. KIRK GROUP / BIODOME International manufactures double membrane gas holder roofs installed on concrete tanks and lagoons for major utilities and dairy farms. On the material supply side, Lucky-Tech Membranes Pvt Ltd in India produces PVC/PVDF-coated fabrics with UV and flame-retardant treatments essential for renewable energy systems.
Technical and Material Dynamics
The operational integrity of a double membrane biogas holder relies heavily on material science. The inner gas barrier typically utilizes PVC-coated high-tenacity polyester fabric membranes, often ranging between 800 to 1500 gsm. These materials are not generic; they incorporate UV stabilizers, flame retardants, and fungicidal treatments to ensure durability against harsh environmental conditions and chemical resistance to biogas components such as hydrogen sulfide (H2S).
Regulatory and safety standards dictate that these gasholders must demonstrate low methane permeation and effective odor containment. Studies have confirmed that minimal migration occurs when using high-quality coated fabrics, making material selection a critical risk mitigation factor. Furthermore, manufacturing processes have evolved to ensure gas-tight integrity. Membranes are increasingly manufactured using radio frequency (RF) welding for 100% gas-tight seams. A key architectural feature is the independence of the inner membrane from the outer air-supported structure, allowing the inner layer to manage gas pressure while the outer layer maintains shape via fan pressure. This dual-layer approach enhances safety and extends the service life of the storage system.
Recent Industry Developments
The period leading into 2026 has seen active deployment and product refinement. Chengdu AMOCO Architecture Technology Co., Ltd. has been particularly active, with multiple installation completions and new project initiations across Asia and South America. These projects underscore the global demand for quick-install membrane storage solutions. YHR Tanks updated their technical documentation and blog in January 2026, confirming ongoing product availability and customization capabilities, signaling confidence in continued supply chain stability. These developments indicate that manufacturers are not only expanding capacity but also reinforcing technical support networks to accommodate international project demands.
Report Methodology and Strategic Value
This market research report is designed as a decision-support tool for executives, investors, and engineering planners. Our methodology combines top-down market sizing with bottom-up validation through primary interviews and secondary data analysis. We assess historical performance from 2020 to 2025 to establish baseline trends before projecting forward to 2032.
Stakeholders will find detailed profiles of key companies, including their headquarters, product portfolios, and recent strategic moves. The report analyzes the competitive intensity and identifies gaps in the market where specialized service or innovative material technology can provide a first-mover advantage. By understanding the fragmentation levels and the specific strengths of incumbents like CENO-TEC, WesTech, and the growing Chinese manufacturers, clients can refine their M&A strategies, partnership formations, or competitive positioning.
Biogas Market
Furthermore, the analysis extends to the downstream applications and regional regulatory environments that influence procurement cycles. For manufacturers, this insight aids in production planning and geographic expansion. For end-users, it provides a vendor evaluation framework to select partners capable of delivering long-term performance under specific operational conditions.
Why This Report Matters for 2026 Decision-Making
As the market moves through the forecast period, the margin for error in capital intensive biogas projects diminishes. Operators need to validate that storage solutions can withstand evolving regulatory scrutiny and material degradation over decades of use. Investors need to pinpoint where growth capital will yield the highest returns in the value chain. This report provides the clarity needed to navigate these complexities.
We do not simply present numbers; we interpret the forces shaping them. Whether you are assessing the viability of a new biogas plant, evaluating potential suppliers for membrane replacement, or analyzing the competitive threat posed by emerging manufacturing hubs in Asia, this research delivers the context required to act with confidence. The data covers revenue in USD Million, providing a standardized metric for financial modeling.
Access to the full suite of segmentation data, including precise regional revenues and application-specific growth rates, is essential for building accurate business cases. While this overview highlights the macro trends and competitive landscape, the complete intelligence is available in the full report. We invite industry leaders to leverage this comprehensive analysis to secure their position in the expanding global double membrane biogas holder market.
For detailed tables, specific growth rates by segment, and a full competitive benchmarking matrix, please refer to the complete Worldwide Double Membrane Biogas Holder Market Research publication. Let this insight be the foundation of your strategic planning for the decade ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Double Membrane Biogas Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Frameless Glass Railing Market to Reach $5.38B by 2032, 6.55% CAGR
By pmarketresearch, 2026-09-16
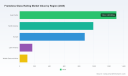
Strategic Horizons in Frameless Glass Railing: Navigating Market Growth and Design Evolution
The global architecture and construction landscape is undergoing a subtle but profound shift in how boundaries are defined. Where once solid walls and opaque barriers dominated the perimeters of modern structures, there is now a prevailing preference for transparency, light, and seamless integration with the surrounding environment. This aesthetic transition has propelled the Worldwide Frameless Glass Railing Market into a position of significant strategic importance for stakeholders across the value chain. As we look toward 2026 and beyond, understanding the intricate dynamics of this market is no longer optional; it is a critical component of informed decision-making for manufacturers, distributors, architects, and investors.
Our latest comprehensive study, the Worldwide Frameless Glass Railing Market Report, offers a granular view of this evolving sector. It is designed not merely as a collection of statistics, but as a strategic toolkit to navigate the complexities of material costs, regulatory compliance, and shifting consumer preferences. The period from 2020 to 2032 tells a story of resilience and steady expansion. Following a market valuation of approximately 2.51 billion USD in 2020, the sector has demonstrated consistent growth, reaching an estimated 3.45 billion USD by 2025. This trajectory underscores a fundamental demand for safety solutions that do not compromise visual appeal.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum. The market is projected to expand from 3.62 billion USD in 2026 to over 5.38 billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 6.55 percent. Such figures indicate that while the market is maturing, it retains substantial room for innovation and capture. For enterprise leaders, this signals a window of opportunity to secure supply chains, optimize product portfolios, and align branding with emerging architectural trends before the market becomes overly saturated.
Structural Preferences and Application Vectors
The adoption of frameless glass railing systems is not uniform across all segments. The report dissects the market into distinct structural categories, highlighting a clear preference among end-users for specific installation types that balance stability with minimalism. Two primary system types dominate the landscape, commanding the majority of revenue share within the sector. There is also a notable presence of standoff pin systems, catering to niche high-end applications where specific aesthetic goals override standard installation protocols.
Beyond the hardware, the application split reveals where the demand is originating. Commercial buildings currently represent the larger portion of revenue generation, driven by high-rise developments, hospitality projects, and public spaces that require robust safety standards without sacrificing views. However, residential buildings constitute a substantial and growing segment. This dual-engine growth suggests that the market is not overly reliant on a single industry vertical. The demand is diversified, buffering the sector against downturns in specific construction sectors. For businesses, this implies potential strategies for diversification across both commercial contract work and residential distribution channels.
Regional Dynamics and Supply Chain Considerations
Geographically, the market exhibits distinct characteristics shaped by local construction booms, regulatory environments, and economic stability. Asia Pacific leads the global revenue landscape, reflecting rapid urbanization and a growing middle class with increased demand for modern home amenities. This region offers significant volume potential but also presents challenges related to logistics and varying local building codes. North America follows as a robust market, characterized by high adoption rates in luxury residential and commercial renovations. Europe maintains a steady presence, driven by strict safety regulations and a established culture of architectural glass usage.
Worldwide Frameless Glass Railing Market
Emerging regions in Latin America and the Middle East and Africa, while currently representing smaller shares of the global revenue, offer frontier opportunities. For market entrants, these regions often require customized approaches regarding pricing strategies and local partnership networks. Supply chain stability is also a critical factor influencing regional competitiveness. Recent analysts insights indicate fluctuations in raw material costs, specifically regarding float glass prices. In December 2025, prices in China reached 1370 USD per metric ton amid oversupply conditions, whereas regional variations such as 1130 USD per metric ton were observed in the USA. Such variances highlight the importance of localized sourcing strategies to protect margins and ensure consistent product availability.
Competitive Landscape and Strategic Positioning
The competitive environment within the frameless glass railing market is characterized by a mix of specialized manufacturers and broader architectural component suppliers. Market concentration remains relatively moderate, with the top three companies holding approximately 18.45 percent of the market and the top five holding about 26.3 percent. This fragmentation suggests that while established players dominate high-visibility segments, there is room for agile competitors to carve out niches through specialization or regional focus.
Several key companies define the current competitive terrain. Q-railing, based in the Netherlands, specializes in high-end systems including the SABCO balustrade system, emphasizing clean lines and structural integrity for architectural applications. In the United States, C.R. Laurence offers comprehensive solutions with dry glaze and wet glaze options along with hardware for interior and exterior use. IG Railing, headquartered in Canada, focuses on sleek, minimalist systems with modular components designed for simple specification and installation. The Glass Railing Store provides high-quality systems for residential and light commercial applications with competitive pricing and fast shipping utilizing stainless steel hardware.
InvisiRail delivers minimalist systems that maximize visibility and open space for decks and patios with modular installation. Vista Railing Systems manufactures systems with posts that maximize unobstructed views using vertical slots for quick installation. Wagner Companies supplies customizable architectural frameless and post-mount systems with shoe moulding options. GRECO Architectural Metals and Railings offers systems tailored for commercial and multi-family construction projects. Empire Railing provides systems designed for maximum transparency and minimalist aesthetics with strong structural detailing. Trex Company produces Signature X-Series frameless glass railings with laminated glass panels and minimalist anchor posts for decks and balconies.
Glass Curtain Wall Market
Other notable participants include Viewrail, which supplies systems focused on safety compliance and modern architectural integration. Lumon, based in Finland, offers balcony railing and enclosure systems with an emphasis on Nordic design and durability. Hartung Glass Industries fabricates custom glass panels including laminated and tempered options for indoor and outdoor use. Glassupply.com manufactures and supplies factory-direct frameless glass fencing and railings with high-grade stainless steel hardware. These players collectively shape the standards for quality, design, and safety in the industry.
Recent Developments and Innovation Trajectories
Innovation remains a key driver of competitive advantage. Recent developments illustrate how companies are responding to the demand for both aesthetics and functionality. In July 2024, Trex Company launched the Signature X-Series Frameless Glass Rail featuring half-inch laminated glass panels that appear to float between minimalist Charcoal Black anchor posts for unobstructed views. Such product launches target the high-end consumer segment willing to pay a premium for visual clarity and design distinctiveness.
Distribution networks are also expanding to meet market needs. In June 2023, Vista Railing Systems partnered with Carolina Atlantic Forest Products to expand distribution of frameless glass railing systems across the southeastern U.S. and Texas. This move highlights the importance of logistical reach in capturing regional market share. Looking at more immediate future activities, in April 2026, Frameless Hardware Company hosted an AIA learning session on Heavy Glass Handrail Systems as part of mid-Atlantic glass industry events. This focus on education and specification support indicates a strategic shift toward engaging architects early in the design process to ensure product selection during the planning phase.
Regulatory Compliance and Risk Mitigation
Navigating the regulatory landscape is perhaps the most critical operational challenge for stakeholders in this market. Building codes dictate not only the safety of the installation but also the materials used. The International Building Code Section 2407 requires glass in guards and handrails to be laminated safety glazing, typically tempered or heat-strengthened, to meet impact and load resistance standards. Compliance with these codes is non-negotiable for manufacturers and installers operating in regulated jurisdictions.
Furthermore, glass used in railing systems must comply with safety glazing standards such as ANSI Z97.1 Class A or CPSC 16 CFR 1201 Category II for impact resistance. Failure to meet these standards can result in liability issues and market exclusion. Guardrail height requirements are typically 36 to 42 inches with maximum opening sizes of 4 inches to prevent passage of a 4-inch sphere per standard building codes. These specifications influence the design dimensions of railing components and must be considered during the engineering phase. For businesses, integrating compliance checks into the product development lifecycle is essential to avoid costly redesigns or rejection of installations.
Strategic Imperatives for 2026 and Beyond
As the market moves through the 2026 to 2032 forecast period, several strategic imperatives emerge for industry participants. First, supply chain resilience must be prioritized given the volatility in raw material pricing seen in recent periods. Second, differentiation through design and installation ease will be crucial as the market matures and price competition intensifies. Companies that can offer modular, easy-to-specify systems while maintaining premium aesthetics are likely to gain favor among architects and contractors.
Third, geographic expansion should be approached with nuance. While Asia Pacific offers volume, local partnerships and understanding of regional building codes are vital. In North America and Europe, the focus may shift toward value-added services such as specification support and compliance documentation. Finally, sustainability and durability are becoming increasingly important. Products like those emphasized by Lumon in Nordic design or Hartung in custom fabrication highlight that longevity and material quality are key selling points in a market where safety and appearance are paramount.
The Worldwide Frameless Glass Railing Market represents a convergence of construction demand, aesthetic evolution, and safety regulation. With a clear growth trajectory and a competitive landscape ripe for strategic maneuvering, the upcoming years offer significant opportunities for those equipped with the right intelligence. To fully leverage these insights, stakeholders require a deeper dive into the data. Our complete research report provides the detailed segmentation analysis, comprehensive vendor profiles, and granular regional data necessary to build a robust market entry or expansion strategy. We invite you to explore the full report to access the precise intelligence needed to steer your organization through the complexities of this dynamic market landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Frameless Glass Railing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Optical Cryostat Market to Hit $386.83M by 2032 with 10.82% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for a Critical Inflection Point: Introducing the Worldwide Cryostation Optical Cryostat Market Research
The precision cooling systems that enable next-generation optical measurements are experiencing a structural shift. As the worldwide Cryostation Optical Cryostat market crosses the $188 million threshold in 2025 and projects a 10.82% compound annual growth rate through 2032, enterprises operating across advanced research, quantum infrastructure, and specialized instrumentation face a rapidly reconfiguring competitive landscape. For executives, procurement leaders, and technology strategists, the window to align capacity planning, R&D investment, and partnership strategy is narrowing. This article outlines why our newly released market research delivers the actionable intelligence required to navigate 2026 and beyond.
The industry is no longer defined by incremental laboratory upgrades. It is being reshaped by converging demand drivers: the expansion of quantum materials research, the maturation of cryogenic measurement ecosystems, and a decisive pivot toward cryogen-free closed-cycle architectures. Understanding how these forces interact—and where capital, talent, and engineering resources should be deployed—requires more than headline growth figures. It demands a granular, scenario-aware view of segmentation dynamics, regional supply chain realities, and the strategic positioning of the firms that dominate this niche but high-value space.
Why 2026 Demands a Forward-Looking Market View
The forecast horizon from 2026 through 2032 reveals a market trajectory that outpaces many adjacent laboratory instrumentation categories. After reaching $188.45 million in 2025, the worldwide revenue base is projected to expand to $204.67 million in 2026, then accelerate toward $254.69 million by 2028 and $386.83 million by 2032. This growth pattern is not uniform across the ecosystem. Instead, it reflects concentrated investment in specific technical configurations, application verticals, and geographic ecosystems that reward organizations with foresight in product roadmapping, vendor partnerships, and specialized service infrastructure.
For corporate strategists, the 2026 outlook carries several implications. First, the shift toward pulse tube and GM cryocooler-based platforms is reducing dependency on consumable cryogens, but it also raises the engineering bar for vibration control, thermal stability, and optical access at sub-4 Kelvin temperatures. Second, the demand for integrated magnetic field capabilities—reaching up to 7T in select platforms—means that optical cryostat procurement is increasingly bundled with magneto-optical experimentation requirements. Third, procurement signals from academic and national research institutions are becoming more customized, with recent sole-source engagements reflecting specifications that include high-frequency coaxial integration, specialized fiber routing, and large sample spaces engineered for high-numerical-aperture optical paths.
Organizations that wait until procurement cycles open will find themselves competing in a constrained supply environment. Those that map the demand trajectory now will be positioned to negotiate long-term supply agreements, align internal R&D with emerging customer specifications, and anticipate where regional demand will concentrate over the next seven years.
Market Structure, Growth Trajectory, and Strategic Implications
The worldwide market for Cryostation optical cryostats has evolved from a fragmented laboratory supply category into a concentrated, technology-intensive segment. Historical revenue progression from 2020 through 2025 demonstrates sustained expansion, but the forecast period reflects a step-change in velocity. This acceleration is underpinned by several structural dynamics that our research unpacks in detail.
One of the defining characteristics of the market is the dominance of closed-cycle architectures. Cryogen-free configurations are increasingly preferred for their operational continuity, reduced consumable costs, and compatibility with automated measurement environments. These systems are designed to eliminate liquid cryogen use while maintaining sample spaces that support complex optical setups and vibration profiles compatible with high-NA optical access down to temperatures below 3.6K. As research teams demand repeatable, low-drift environments for quantum optics and magneto-optical experiments, the engineering requirements for closed-cycle platforms continue to tighten, favoring manufacturers with mature cryocooler integration capabilities and robust mechanical design.
Application demand is equally multifaceted. Quantum computing and information research drives a significant share of procurement, reflecting the need for ultra-low vibration environments and precise temperature control across ranges that span from approximately 1.7K to 350K. Optical spectroscopy, microscopy and imaging, and materials science research each bring distinct technical requirements, from UV to IR window configurations for Raman, FTIR, and NMR-compatible systems, to customized probe stations with integrated optical access. Our research examines how these application segments interact with product architecture choices and how procurement patterns diverge across research-intensive institutions versus commercial R&D environments.
Geographically, the market reflects uneven demand intensity and distinct supplier ecosystems. Regional demand patterns are shaped by the concentration of advanced research institutions, national quantum initiatives, and localized service and support networks. Understanding where demand is emerging, which customs and procurement frameworks dominate, and how logistics and technical support influence total cost of ownership is essential for anyone evaluating market entry, distribution partnerships, or manufacturing footprint decisions.
Competitive Landscape: Who Is Shaping the Next Generation of Optical Cryostats
The competitive field is defined by a small group of highly specialized manufacturers whose product roadmaps, demonstration activity, and technical differentiation directly influence procurement decisions. Our research profiles the firms that are actively setting performance benchmarks, expanding application coverage, and signaling where the market is heading.
Montana Instruments has reinforced its position through a focus on cryogen-free closed-cycle optical cryostats designed for low-vibration optical and electrical measurements. Its flagship Cryostation s200 platform, with a 200mm sample space and temperature range from 3.6K to 350K, exemplifies the performance envelope that quantum materials research teams increasingly expect. The company's continued presence at major industry gatherings—including World of Quantum 2025 in Munich, MRS Fall 2025 in Boston, and the APS Global Physics Summit in Denver—signals sustained engagement with the research community and a deliberate strategy to align product visibility with high-impact application domains. The introduction of the Cryostation 200 PT further underscores an emphasis on stability, automation, and specialized measurement workflows.
Quantum Design has pushed the integration boundary with the OptiCool platform, a cryogen-free magneto-optical cryostat spanning 1.7K to 350K with high optical access and a 7T split-coil magnet. The recent announcement of the OptiCool Vector, featuring a 4-1-1 vector magnet configuration for advanced magneto-optical experiments, illustrates how manufacturers are responding to demand for multi-axis field control in optical measurement environments. These product moves matter because they reshape the specification conversation: procurement teams are no longer comparing standalone cooling performance alone, but evaluating integrated magnetic and optical capabilities as a bundled research-enabling solution.
attocube systems GmbH continues to differentiate through compact closed-cycle platforms such as the attoDRY series, which emphasizes large sample spaces, low vibrations, and unobstructed optical access for magneto- and quantum optical applications. The introduction of the attoCMC line for rack-compatible sub-4K mobile cryogenics reflects a broader industry trend toward flexible, space-efficient configurations that fit within demanding laboratory layouts while preserving experimental performance.
Lake Shore Cryotronics, Advanced Research Systems, and Oxford Instruments (Andor) each bring distinct value propositions. Lake Shore's window sets for UV to IR access and its support for Raman, NMR, and FTIR spectroscopy applications address a broad optical measurement footprint. Advanced Research Systems contributes ultra-low vibration models such as microDrift for quantum optics, alongside custom flow cryostats and probe stations with optical access. Oxford Instruments' Cryofree OptistatDry series, with top- or bottom-loading options, reinforces the market's demand for temperature-controlled optical measurement platforms that integrate cleanly into spectroscopy and microscopy workflows.
Importantly, the market is not a free-for-all. Consolidated concentration metrics indicate that a limited number of firms account for a substantial share of revenue, which means competitive dynamics are shaped as much by ecosystem lock-in, service reliability, and specification familiarity as by price. Our research examines how these firms position themselves across type, application, and regional demand, and where white space or over-served segments may create opportunities for differentiated offerings.
What the Report Delivers: Actionable Intelligence for Decision-Makers
This study is built for executives who need more than directional commentary. It provides a structured, decision-oriented view of the worldwide Cryostation Optical Cryostat market, with explicit attention to the operational questions that determine procurement success, product strategy, and investment timing.
The report covers the historical period from 2020 to 2025 and extends forecast analysis through 2032, allowing readers to connect past demand behavior with forward-looking scenarios. It evaluates the market across three analytical dimensions: type, application, and region. By disaggregating demand in this way, the study helps readers understand which product architectures are gaining traction, which application verticals are expanding procurement intensity, and where regional demand is likely to concentrate.
Key components of the report include:
- Detailed segmentation analysis that clarifies how closed-cycle and open-cycle configurations divide the market and how each type aligns with distinct user requirements, vibration tolerances, and optical access needs.
- Application-level insight that differentiates demand drivers across quantum computing and information, optical spectroscopy, microscopy and imaging, and materials science research, with attention to the technical thresholds that shape purchasing decisions.
- Regional demand and supply context that helps organizations assess where procurement activity is intensifying, how local service infrastructure affects adoption, and what logistical or customization considerations influence total cost of ownership.
- Competitive profiling of leading manufacturers, including product positioning, recent launches, demonstration activity, and procurement signals that reveal how the market is evolving in near-real time.
- Strategic scenario framing that supports capacity planning, partnership evaluation, and product roadmap decisions by connecting technical trends to commercial outcomes.
- Practical guidance on regulatory and classification considerations, including the fact that research-grade optical cryostats for laboratory applications are generally treated as general laboratory equipment rather than medical devices, which has implications for compliance workflows, procurement categorization, and cross-border trade planning.
Our objective is to give decision-makers a clear line of sight from market structure to action. Whether you are evaluating vendor selection, planning a specialized manufacturing or distribution entry, or aligning internal R&D with emerging demand, the study is designed to reduce ambiguity and support defensible strategy choices.
Market Dynamics Shaping 2026 and Beyond
Several interlocking dynamics will determine how the market unfolds over the forecast period. First, the demand for low-vibration, cryogen-free environments is no longer a niche preference; it is becoming a baseline requirement for research programs that depend on reproducible optical and electrical measurements. This creates a performance ceiling that rewards manufacturers with mature cryocooler integration and penalizes those that cannot consistently deliver thermal stability, low drift, and unobstructed optical paths.
Second, the convergence of optical access with magnetic field capability is redefining specification packages. As research increasingly requires magneto-optical experiments across a wide temperature envelope, buyers are evaluating platforms that combine cooling performance, magnet integration, and optical geometry in a single, coherent system. This bundling effect favors vendors that can offer integrated solutions and also creates opportunities for organizations that can provide specialized accessories, calibration services, or application-specific customization.
Third, procurement behavior is becoming more project-specific and specification-intensive. Recent procurement activity from research institutions demonstrates a move toward customized high-capacity closed-cycle systems with specialized coaxial and fiber integration. These engagements signal that end users are no longer treating optical cryostats as interchangeable catalog items; they are engineering them into broader experimental architectures. For suppliers and channel partners, this means that flexibility, lead-time management, and application engineering support are becoming as important as core product performance.
Fourth, the operational advantages of cryogen-free systems are reshaping total cost of ownership discussions. Eliminating recurring liquid cryogen dependence improves workflow continuity and reduces logistical complexity, but it also shifts value toward initial capital expenditure, service contracts, and long-term reliability. Organizations evaluating procurement strategies should weigh not only sticker price, but also downtime risk, service availability, and the compatibility of a platform with planned future experiments.
Worldwide Optical Cryostat for Microscopy Market
Finally, the market's classification as general laboratory equipment—rather than a regulated medical device category—streamlines certain compliance considerations, but it does not eliminate the need for rigorous vendor evaluation. Research users continue to require systems designed exclusively for laboratory and research applications, with performance claims grounded in measurable vibration, temperature stability, and optical access characteristics. This reinforces the importance of manufacturer documentation, application-specific validation, and transparent specification language when comparing alternatives.
Why This Research Matters for Your 2026 Strategy
The worldwide Cryostation Optical Cryostat market is entering a phase in which strategic advantage will belong to organizations that understand not just that demand is growing, but where that growth is concentrated, why it is emerging, and how it will reshape procurement, product design, and competitive positioning. Our study is engineered to provide that understanding without overwhelming readers with disconnected statistics. Instead, it connects market size, growth trajectory, segmentation behavior, competitive activity, and application-specific dynamics into a coherent decision framework.
Worldwide Cryostation Optical Cryostat Market
For companies evaluating market entry, the research clarifies where demand intensity is highest and what technical and service capabilities are required to compete credibly. For existing manufacturers and distributors, it identifies where specification expectations are rising, which application verticals are expanding fastest, and how recent product launches and demonstration activity are reshaping buyer expectations. For procurement teams and research administrators, it provides the context needed to assess vendor claims, anticipate customization requirements, and evaluate total cost of ownership across different architectural choices.
Most importantly, the study is designed to support timely action. The forecast period through 2032 is long enough to warrant durable investment decisions, yet near-term dynamics in 2026 will set the tone for supply availability, competitive intensity, and specification standards. Organizations that gain clarity now will be better positioned to structure partnerships, allocate engineering resources, and respond to procurement opportunities with confidence rather than reaction.
To access the full segmentation breakdown, regional demand analysis, application-level projections, and detailed competitive profiling, we invite you to explore the complete Worldwide Cryostation Optical Cryostat Market research. The published report provides the depth required to convert market intelligence into concrete strategic moves in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cryostation Optical Cryostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVP for Lithium Ion Battery Market Hits $342.15M in 2025, Forecasts 11.24% CAGR to $721.18M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Energy Transition: The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market 2026-2032
The global transition toward electrified mobility and stationary energy storage has fundamentally altered the demand dynamics for specialty chemicals used in battery manufacturing. Among these materials, Polyvinylpyrrolidone (PVP) has emerged as a critical enabler for performance optimization in lithium-ion battery production. As manufacturers scale capacity to meet the projected demand through the end of the decade, understanding the nuanced market structure of battery-grade PVP is no longer optional—it is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip industry stakeholders with the actionable intelligence required to navigate the complexities of the 2026-2032 forecast period.
This analysis serves as a prelude to our full report, offering a high-level perspective on market direction while underscoring the depth of granular data available to clients who require precision for supply chain planning, R&D allocation, and competitive positioning.
Macro Market Trajectory and Revenue Outlook
The financial trajectory of the PVP market for lithium-ion batteries indicates robust expansion, driven by the dual engines of electric vehicle (EV) adoption and energy storage system (ESS) deployment. Analysis of historical performance from 2020 through the base year of 2025 reveals a consistent upward trend in revenue generation, reflecting the materialization of demand forecasts that were previously considered ambitious.
Binders for Lithium Ion Batteries Market
In 2020, the global market revenue stood at approximately 164.2 million USD. By 2025, this figure had climbed to 342.15 million USD, demonstrating a compound growth pattern that outpaces many traditional industrial chemical segments. The report projects that this momentum will accelerate into the forecast period. Revenue is expected to reach 376.25 million USD in 2026 and continue its ascent to 721.18 million USD by 2032. This growth path implies a significant increase in consumption volume as battery factories operationalize gigafactory-scale production lines worldwide.
Our modeling indicates a robust compound annual growth rate (CAGR) of 11.24 percent throughout the forecast horizon. This rate suggests that PVP will maintain its criticality in battery chemistries, resisting substitution by alternative binders or dispersants in the near term. For strategists, this CAGR is not merely a percentage; it represents the velocity at which market share can be captured or lost depending on supply chain resilience and product specification alignment.
Segmentation Dynamics: Type, Application, and Regional Distribution
While the aggregate numbers signal growth, the strategic value of this report lies in its dissection of the market into actionable segments. The study provides a detailed breakdown of the market by product type, application, and region, revealing where value is being created and where supply bottlenecks may emerge.
Product Type Dynamics
The market is bifurcated into Powder PVP and Solution PVP. Powder PVP continues to command a significant share of the market revenue, driven by its logistical advantages in bulk transport to battery manufacturing hubs and its versatility in dry mixing processes. However, Solution PVP is carving out a distinct niche, particularly in facilities where immediate slurry preparation is prioritized over long-term storage stability. Our analysis details the revenue contribution and volume trends of each type, highlighting the specific technical requirements that drive purchasing decisions in automated mixing lines versus manual formulation setups. Clients will gain insight into which form factor aligns best with their processing logistics and cost structures.
Application Criticality
In terms of application, the report segments demand across Carbon Nanotube Dispersant, Electrode Binder Additive, and Ceramic Coating for Separators. Historically, the use of PVP as a dispersant for conductive additives, such as carbon nanotubes and carbon black, has been a primary driver of volume. The ability of PVP to stabilize these conductive networks in the electrode slurry directly impacts the electrical performance and cycle life of the final cell.
Concurrently, the role of PVP in ceramic coating for separators is gaining traction. As battery safety requirements tighten with higher energy densities, the use of PVP-based binders in separator coatings offers adhesion and thermal stability benefits. The Electrode Binder Additive segment also remains substantial, particularly for specific anode and cathode chemistries where adhesion to the current collector is paramount. The full report quantifies the revenue splits across these applications, revealing which function is acting as the primary volume driver in different production environments and how the mix is expected to shift as battery architectures evolve.
Regional Landscape
Geographically, the Asia Pacific region stands as the dominant consumer and producer of battery-grade PVP, reflecting the concentration of global battery cell manufacturing capacity. The market data reflects substantial revenue generation within this region, supported by the presence of major battery manufacturers and downstream EV assembly plants. Europe and North America represent mature but growing markets, driven by local content requirements and the establishment of new gigafactories in Western economies. The Rest of World segment, while smaller in absolute terms, shows potential for incremental growth as battery adoption expands in emerging markets.
The full report provides detailed regional revenue figures and forecasts, allowing companies to assess market attractiveness by territory. It examines the interplay between local production capabilities and import reliance, identifying where tariff structures or logistics costs may influence the final landed cost of PVP materials.
Competitive Landscape and Industry Dynamics
The market structure for battery-grade PVP is characterized by a mix of global specialty chemical giants and agile regional manufacturers. Our analysis of the competitive landscape reveals a moderately concentrated market, with the top three companies holding a combined market share of approximately 64.25 percent, while the top five firms account for roughly 79.1 percent of total revenue. This concentration suggests that while incumbents hold significant sway, there is room for specialized players to capture niche segments through performance differentiation.
Key Market Participants
Ashland Inc. (Wilmington, Delaware, USA) remains a prominent supplier of PVP K-Series polymers used as binders and additives. Their portfolio includes specialty binders like Soteras CCS-V for separators, emphasizing performance polymers for enhanced coating and electrochemical properties. Ashland's focus on high-performance solutions positions them as a preferred supplier for premium-tier battery applications where performance margins are narrow.
BASF SE (Ludwigshafen, Germany) provides PVP for lithium-ion battery applications primarily as dispersants and processing aids in electrode formulations. Their extensive portfolio of additives for cathode, anode, and separator coatings allows them to offer integrated solutions for slurry stability. BASF leverages its global scale to maintain consistent supply chains across major production regions.
In China, the competitive field is diverse and includes several specialized producers. Boai NKY Pharmaceuticals Ltd (NKY Medical) in Jiaozuo, Henan, is a major producer offering battery-grade PVP K30 powder specifically developed for lithium battery applications, supplying high-purity grades for dispersant use. NIPPON SHOKUBAI Co., Ltd. (Osaka, Japan) manufactures PVP used as dispersants for metal oxides and carbon materials, supporting electrode slurry formulation and performance enhancement.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Synvent Materials Corporation (Ningxia, China) offers Syno® PVP Battery Grade (e.g., K30 Battery with K-value 27-32.4, >98% solids, <100 ppm NVP) manufactured under cGMP standards. This focus on high purity and certification makes them relevant for applications where impurity control is critical. Henan Pengfei New Materials Co., Ltd. produces PVP series for lithium battery cathode slurries and nano materials, emphasizing dispersant roles. Their recent technical updates in 2025 have highlighted performance data on PVP as nonionic dispersants, showcasing improved stability and processing efficiency. Huzhou Sunflower Specialty Polymer Co., Ltd. in Zhejiang is another leading manufacturer of PVP K-series, supplying PVP as dispersant for lithium battery cathode materials.
While these companies represent the core competitive set, the full report profiles additional entities and analyzes their specific revenue contributions, capacity expansions, and strategic partnerships. It dissects the moves made by these players, such as technical application updates and product launches, to reveal the direction of innovation in the sector.
Critical Market Drivers and Headwinds
Understanding the market trajectory requires a clear view of the forces shaping supply and demand. The report integrates several dynamic factors that influence pricing, availability, and margin structures.
Raw Material Constraints and Costs
The upstream feedstock for PVP, N-vinylpyrrolidone (NVP), relies on commodities such as calcium carbide and acetylene. The cost of these raw materials forms a significant portion of the total production cost for battery-grade PVP. Demand for PVP in lithium batteries and photovoltaic silver paste has risen sharply in recent years, contributing to price premiums for high-purity grades. There is an industry expectation that demand will continue to escalate, putting upward pressure on feedstock availability. Furthermore, environmental restrictions on chemical industrial parks in China have occasionally led to imbalances in NVP supply, impacting the availability of high-purity battery-grade PVP. These supply-side frictions can lead to volatility in pricing and require proactive supply chain management.
Price Volatility and Cost Structures
Historical price data indicates that PVP prices have fluctuated within a notable range over recent periods, influenced by raw material costs and demand from the new energy sector. For procurement teams, this volatility underscores the need for long-term contracts, hedging strategies, or vertical integration considerations. The report examines price trends and correlates them with capacity utilization rates and feedstock index movements to help clients anticipate cost cycles.
Usage Intensity and Specification Trends
The intensity of PVP usage per unit of battery capacity is a key metric for forecasting demand. Industry benchmarks suggest specific usage rates for PVP in lithium battery applications, primarily involving industrial-grade PVP K30 and K90 as dispersants for cathode materials. As cathode chemistries evolve toward higher nickel contents or silicon blends, the specification requirements for binders and dispersants may shift, potentially altering the consumption rate or driving demand for higher purity grades. Our study analyzes these technical trends to project how usage intensity might evolve over the forecast period.
Report Architecture and Analytical Depth
The "Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market" report is structured to guide decision-makers from macro trends to micro-level execution details. Beyond the market sizing and segmentation discussed above, the full document includes:
- Historical Reconstruction (2020-2025): A detailed year-by-year breakdown of market performance, allowing for validation of internal models against external data and identification of anomaly periods caused by supply disruptions or demand shocks.
- Forecast Methodology (2026-2032): Transparent modeling assumptions regarding capacity additions, technology adoption curves, and regional growth drivers. The forecast accounts for known pipeline projects and policy interventions that may alter market equilibrium.
- Competitive Benchmarking: In-depth profiles of key companies, including their product portfolios, production capacities, geographic footprint, and recent strategic developments. The report assesses the relative positioning of each player in terms of price, quality, and service.
- Segment Revenue and Volume Analysis: Granular data splits for region, type, and application. These splits are essential for companies to identify high-growth pockets and allocate resources accordingly.
- Supply Chain and Raw Material Analysis: An examination of the NVP supply chain, cost structures, and the impact of environmental regulations. This section helps stakeholders assess risk exposure in their upstream dependencies.
- Strategic Recommendations: Actionable insights for suppliers, buyers, and investors. This includes guidance on market entry strategies, partnership opportunities, and risk mitigation tactics.
Our research team has synthesized data from public filings, industry surveys, technical literature, and primary interviews to construct a cohesive narrative. The result is a document that not only tells you what the market is doing but explains why it is doing it and what it means for your specific business context.
The 2026 Strategic Imperative
As the industry enters 2026, the window for aligning strategy with market realities is narrowing. The projected growth to 2032 indicates a market that will be significantly larger and potentially more complex than it is today. Companies that rely on aggregate data alone may miss the nuances of regional shifts, application-specific demand surges, or competitive moves by niche players.
For suppliers, the opportunity lies in capturing share in high-growth segments by differentiating on purity, consistency, or technical support. For battery manufacturers, the focus must be on securing reliable supply of grade-specific materials while managing cost volatility through strategic sourcing. For investors, understanding the concentration dynamics and the emergence of new capacity is vital for evaluating the risk-return profile of assets in this value chain.
The full report provides the data backbone required to make these decisions with confidence. It quantifies the revenue opportunities in each segment, maps the competitive threats, and highlights the supply chain vulnerabilities that could disrupt operations. By accessing this intelligence, organizations can move beyond reactive planning to proactive strategy execution.
Conclusion
The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market is at a pivotal juncture. The convergence of electrification mandates, battery chemistry innovation, and raw material dynamics creates a landscape rich with opportunity but fraught with complexity. PW Consulting's comprehensive study offers the clarity needed to navigate this environment.
While this overview highlights the macro trajectory and structural dynamics, the precise segmentation data, detailed competitive rankings, and scenario-based forecasting remain within the full report. We invite industry leaders, procurement directors, and strategy teams to access the complete intelligence package to ensure their 2026 planning is built on a foundation of rigorous, up-to-date analysis.
Request the Full Report and Detailed Segmentation Data
For detailed analysis of this topic, please visit the official page: Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pharmaceutical L-Carnitine Market Hits $245.5M in 2025, 5.45% CAGR Forecast to 2032
By pmarketresearch, 2026-09-16
Navigating the Global Pharmaceutical Grade L-Carnitine Market: A 2026 Strategic Overview
The global pharmaceutical landscape is witnessing a subtle yet significant shift in the nutritional pharmacotherapy sector, with Pharmaceutical Grade L-Carnitine emerging as a critical compound for clinical nutrition, metabolic support, and therapeutic interventions. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from API manufacturers to pharmaceutical distributors and healthcare investors. PW Consulting latest comprehensive market research provides a definitive lens through which to view these dynamics, offering a granular analysis of the value chain, competitive forces, and regulatory hurdles that define this sector.
This market, driven by an aging global population and increasing awareness of metabolic health, has demonstrated resilience and structured growth over the past half-decade. Our analysis indicates that the market reached a valuation of approximately 245.5 million USD in 2025, reflecting a steady upward trend from 187.65 million USD in 2020. Looking ahead, the forecast period spanning 2026 to 2032 suggests a continued expansion, with the market projected to reach 355.95 million USD by the end of the forecast window. This trajectory corresponds to a Compound Annual Growth Rate (CAGR) of 5.45 percent, signaling a stable, mature growth environment rather than a volatile speculative bubble. For decision-makers, this consistency implies predictable revenue streams but also necessitates precise positioning to capture share in a consolidating landscape.
Structural Dynamics and Value Chain Complexity
The pharmaceutical grade L-Carnitine ecosystem is defined by rigorous quality standards that separate it distinctly from bulk industrial or feed-grade variants. Industry data suggests that pharmaceutical-grade material commands a significant price premium, often ranging from three to five times higher per kilogram than feed-grade counterparts. This pricing power is underpinned by the stringent purity requirements mandated for human consumption, particularly in injectable forms where safety profiles are paramount. Manufacturers must adhere to USP 43 and EP 10.0 standards, which include strict GMP manufacturing protocols and endotoxin limits below 0.05 EU/mg for injectable grades. These regulatory barriers create a high entry threshold, naturally favoring established players with robust quality assurance infrastructures.
Production capabilities remain a central bottleneck. Both fermentation and chemical synthesis processes for high-purity L-Carnitine face capacity constraints, which has driven a trend toward vertical integration among producers. Companies are increasingly seeking control over raw material sourcing and bioprocess capabilities to ensure consistent quality and supply security. This vertical integration is not merely operational but strategic, as it mitigates the risk of supply chain disruptions that could compromise clinical supply agreements. The market concentration reflects this maturity, with the top three competitors holding a significant portion of the revenue share, indicating that scale and compliance are key determinants of market leadership.
Segmentation and Therapeutic Applications
While the aggregate numbers tell a story of growth, the true strategic value lies in understanding where that value is generated. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of chemical forms, the landscape includes L-Carnitine Base, L-Carnitine Tartrate, Acetyl-L-Carnitine, and other variants. Each form serves distinct therapeutic niches; for instance, Acetyl-L-Carnitine is often associated with neurological support, while tartrate forms are prevalent in metabolic and nutritional formulations. The distribution of revenue across these types highlights the dominance of specific chemical structures in current clinical practice, though the demand for specialized forms continues to evolve with emerging research.
Worldwide Pharmaceutical Grade Taurine Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region represents a substantial volume contributor, driven by domestic manufacturing capabilities and growing healthcare infrastructure. North America and Europe maintain strong positions, largely influenced by established reimbursement pathways and high adherence to clinical nutrition guidelines. However, the dynamics vary significantly by jurisdiction. In China, for example, specific pharmaceutical products have historically held considerable market share in hospital settings, reflecting established reimbursement pathways in clinical nutrition. This regional nuance is critical for companies looking to expand their footprint, as regulatory environments and procurement mechanisms differ vastly between tenders in Europe and hospital procurement in Asia.
Application-wise, the market is driven primarily by Intravenous Injections and Oral Dosage Forms, with Clinical Nutrition also representing a significant pillar. The dominance of intravenous formulations underscores the critical role of L-Carnitine in acute care and hospital-based metabolic support. Oral dosage forms, meanwhile, cater to chronic management and outpatient supplementation. The balance between these application routes influences manufacturing requirements, as injectable grades require stricter sterility and purity controls compared to oral intermediates. Understanding the revenue split between these applications helps manufacturers align their production capacities with the highest value segments.
Competitive Landscape: Giants and Specialists
The competitive environment is a mix of global life sciences giants, specialized European manufacturers, and large-scale Chinese producers. Leading the pack is the Lonza Group, based in Basel, Switzerland. With over 30 years of expertise, Lonza offers high-purity Carnipure L-Carnitine in crystalline and tartrate forms, manufactured via bioprocess and chemical synthesis. Their strength lies in quality-compliant production for clinical nutrition and supplements, positioning them as a preferred partner for high-value pharmaceutical applications. Similarly, Merck KGaA, including Sigma-Aldrich, supplies high-purity L-Carnitine for pharmaceutical-grade and laboratory applications, supporting clinical and research needs with analytical standards and GMP-compliant materials.
In Europe, Alfasigma (Sigma-tau) maintains a strong hospital market presence with their CARNITENE product. Their strategy involves distribution and promotional activities in key regions, including China, where they have navigated complex market redeployment strategies to maintain brand visibility. Biosint S.p.A. in Italy also contributes to the European supply chain, focusing on USP/EP compliance for API and clinical nutrition formulations. These European players leverage regulatory expertise and brand heritage to command premium positioning.
On the other side of the spectrum, Chinese manufacturers play a pivotal role in global supply. Northeast Pharmaceutical Group Co., Ltd. (NEPG) is a major producer of L-carnitine series including pharmaceutical-grade API, with integrated chemical raw materials and GMP-compliant manufacturing for domestic and export markets. Liaoning Koncepnutra Co., Ltd. operates as one of the largest professional production bases in China, focusing on nutrition ingredients and pharmaceutical chemical intermediates with GMP standards. Hubei Truevita Pharmaceutical Co., Ltd. has scaled significantly, with annual capacity reaching 1500 tons in the first phase, supplying chemical APIs, food additives, and feed additives under high-standard operations. Ningxia Kunzheng Biotechnology Co., Ltd. further expands capacity with a 3000-ton annual production project for L-carnitine and its salts, operational since late 2021.
Other significant players include Chengda Pharmaceuticals Co., Ltd., offering L-carnitine with USDMF and WC documentation for pharmaceutical-grade API supply, and Apino Pharma Co., Ltd., a GMP-certified supplier with CoA, MSDS, and USDMF for API markets. Changzhou Comwin Fine Chemicals Co., Ltd. and Sandoo Pharmaceuticals and Chemicals Co., Ltd. also provide GMP, ISO9001, and FDA-approved sources for export. AgEx Pharma, based in India/USA, operates as a cGMP bulk manufacturer with substantial monthly capacity for pharma and food-grade applications. Rochem International, Inc. serves as a distributor and supplier in the United States with extensive GMP and regulatory documentation. Kaiyuan Hengtai Nutrition Co., Ltd. rounds out the specialized manufacturer group focusing on nutrition and pharmaceutical applications. This diverse competitive set means that buyers have options ranging from high-cost, high-touch European suppliers to high-volume, cost-competitive Asian manufacturers, depending on their specific quality and price requirements.
Recent Market Developments and Strategic Shifts
The period leading into 2026 has been marked by specific corporate actions and product innovations that reshape the competitive terrain. In January 2025, Otsuka Pharmaceutical Factory launched the ENSOLID semi-solid enteric nutrition formula incorporating pharmaceutical-grade L-Carnitine. This launch targets fatty acid metabolism support in clinical and geriatric health settings, signaling a move toward integrated nutritional solutions rather than standalone ingredients. Such product launches expand the addressable market by embedding L-Carnitine into broader care regimens.
Conversely, portfolio rationalization is also occurring. In December 2024, BASF SE signed a binding agreement to divest its Food and Health Performance Ingredients business, which includes production facilities tied to the L-Carnitine production chain. This divestiture suggests a strategic shift among large conglomerates to focus on core competencies, potentially opening opportunities for specialized buyers or competitors to acquire assets and capacity. Meanwhile, Balchem Corporation reported strong growth in its Human Nutrition & Health segment in April 2025, including L-Carnitine and related functional ingredients, indicating sustained demand in the nutrition sector.
Regulatory and market access dynamics continue to evolve. Levocarnitine remains the generic ingredient in multiple approved injectable and oral formulations. Recent ANDA approvals and expirations, such as the Deva Holding As product expiring in June 2025, influence generic competition levels. In China, historical data showed established products holding significant market share in the hospital carnitine market, valued at billions of RMB, reflecting the importance of reimbursement pathways. These dynamics require constant monitoring, as changes in patent status or reimbursement policies can rapidly alter market shares.
Strategic Imperatives for 2026 and Beyond
For stakeholders navigating this market in 2026, several strategic imperatives emerge from the data. First, supply chain resilience is paramount. Given the capacity bottlenecks in fermentation and synthesis, securing reliable sources of API is critical. Vertical integration or long-term contracts with key producers like Lonza or major Chinese GMP-certified facilities can mitigate supply risk. Second, regulatory compliance must be viewed as a competitive advantage. With endotoxin limits and USP/EP standards acting as gatekeepers, manufacturers who can demonstrably exceed these requirements will secure premium contracts in sensitive applications like intravenous injections.
Third, geographic diversification is essential. While Asia Pacific offers volume and growth, North America and Europe offer stability and higher margins due to established reimbursement structures. Companies must tailor their go-to-market strategies to these regions, understanding that distribution channels and procurement rules differ. Fourth, innovation in formulation offers growth potential. The launch of semi-solid enteric formulas by players like Otsuka suggests that combining L-Carnitine with other nutritional elements can unlock new value pools in clinical nutrition.
Finally, the market concentration indicates that M&A activity or strategic partnerships could reshape the landscape. With a significant portion of revenue held by the top competitors, smaller players may need to specialize or form alliances to remain relevant. The divestiture by BASF and the strong growth reported by Balchem highlight that capital is flowing toward specific segments of the nutrition value chain, and investors should align their portfolios accordingly.
PW Consulting comprehensive research report delves deeper into these trends, offering detailed segmentation analysis, granular country-level data, and proprietary forecasts that go beyond the macro overview presented here. While the high-level growth rates and total market values provide a necessary context, the true decision-making intelligence lies in the specific regional splits, application breakdowns, and competitive benchmarking contained within the full study. Understanding the exact allocation of revenue across types, the specific growth drivers in each region, and the detailed operational profiles of every key competitor requires access to the complete dataset.
In an environment where premium pricing relies on compliance, where capacity constraints dictate supply security, and where regional reimbursement pathways determine market access, having granular intelligence is not optional—it is essential. The projected growth to 355.95 million USD by 2032 represents a significant opportunity, but capturing it requires navigating a complex web of regulatory, operational, and competitive factors. This introduction serves as a primer to the landscape, but the full strategic roadmap requires the depth of analysis that only our complete market research can provide. Stakeholders are encouraged to leverage this intelligence to refine their sourcing strategies, identify partnership opportunities, and forecast their revenue potential with precision in the evolving global pharmaceutical grade L-Carnitine market.
Worldwide Pharmaceutical Grade L-Carnitine Market
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SocialFi NFT Market Hits $480M in 2025, Projected to Reach $1.09B by 2032
By pmarketresearch, 2026-09-16
Beyond Likes: The Strategic Imperative of SocialFi NFTs in 2026
The convergence of decentralized social networks and non-fungible token (NFT) technology has moved beyond speculative experimentation into a structured economic layer for digital interaction. As we navigate the midpoint of 2026, the SocialFi NFTs market stands at a critical inflection point. What was once a niche intersection of Web3 experimentation is now a validated infrastructure for creator ownership, community governance, and social monetization. For enterprise leaders, venture capitalists, and product strategists, understanding this landscape is no longer optional—it is essential for positioning within the next generation of digital economies.
This article serves as a strategic introduction to our latest comprehensive market research report on SocialFi NFTs. It outlines the macro-economic trajectory, the evolving competitive architecture, and the operational depth contained within the full study. However, like any high-value intelligence briefing, this overview acts as a trailer: it demonstrates the rigor and scope of our analysis while reserving the precise segmentation figures and proprietary forecasts for the complete report. Decision-makers who require granular data to validate investment theses or product roadmaps are encouraged to access the full document.
A Macro Growth Trajectory Defined by Digital Ownership
The financial architecture of the SocialFi NFTs market demonstrates a consistent upward trajectory, signaling a shift from early-adopter volatility to sustained institutional and consumer adoption. Analyzing historical performance from 2020 through the base year of 2025 reveals a market that has expanded its revenue foundation significantly. In 2020, the market operated at a modest scale, but by 2025, the revenue base had grown to approximately 480 million USD. This escalation is not merely a function of speculative trading but reflects the integration of NFT primitives into social applications that users engage with daily.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is expected to reach roughly 539 million USD in 2026, accelerating toward an estimated 1.09 billion USD by the end of the forecast window in 2032. This growth is underpinned by a compound annual growth rate that underscores the durability of the asset class within the broader social technology sector. Such figures suggest that SocialFi NFTs are transitioning into a core component of the digital creator economy rather than a peripheral innovation. For stakeholders, this implies a need to evaluate long-term infrastructure plays rather than short-term hype cycles. The revenue unit consistency across the forecast period allows for clear planning, though the specific allocation of these revenues across different verticals requires deeper segmentation analysis available in our full dataset.
It is important to note the concentration dynamics within this expanding market. Current metrics indicate a competitive environment where no single entity dominates completely, yet top players hold significant sway. The combined market share of the top three firms hovers around 35.5 percent, while the top five entities control approximately 42.8 percent. This distribution suggests a fragmented but maturing landscape where innovation speed and user retention are the primary drivers of market share acquisition. For enterprises entering this space, this concentration data highlights the opportunity for disruption in underserved niches while acknowledging the barriers to entry posed by established protocol layers.
Segmentation: Types and Applications Driving Utility
The utility of SocialFi NFTs is not monolithic. Our research dissects the market across three primary types that define how digital assets are utilized within social contexts. The first category involves Identity and Decentralized Identifier (DID) NFTs, which serve as the foundational layer for user sovereignty and portable reputations across chains. The second, and currently substantial, portion of the market comprises Creator Monetization NFTs, which enable direct economic relationships between content producers and their audiences. The third category includes Membership and Access Passes, which function as gating mechanisms for communities, exclusive content, or governance rights.
Worldwide Fashion Influencer Market
These types manifest through distinct application vectors. Decentralized Social Platforms represent the largest application segment, utilizing NFT infrastructure to power on-chain social graphs and content ownership. Creator Economy Marketplaces form the second major application layer, facilitating the trading of digital collectibles and tipping mechanisms. The third application domain lies within DAO Governance Ecosystems, where NFTs act as voting tokens and participation credentials. Each of these application areas interacts differently with user behavior and revenue models. For instance, while decentralized platforms focus on network effects, marketplaces prioritize liquidity and trading volume. A nuanced understanding of these operational differences is critical for solution providers aiming to target specific user needs without applying a one-size-fits-all strategy.
Furthermore, geographic distribution plays a pivotal role in how these segments perform. The market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each with varying levels of regulatory clarity and digital infrastructure maturity. While aggregate numbers show a balanced global interest, regional adoption rates differ based on local creator ecosystems and blockchain infrastructure availability. Detailed regional breakdowns, including specific market values and growth percentages by territory, are provided in the full report to assist multinational strategies in prioritizing market entry or expansion efforts.
Competitive Landscape: Protocols Shaping the Social Web
The competitive landscape of the SocialFi NFTs market is characterized by a mix of established protocols, innovative platforms, and specialized marketplace providers. Leading this space is Friend.tech, based in San Francisco, which has pioneered the concept of trading shares in creators to monetize social interactions. Their integration of NFT profiles has set a precedent for linking social capital directly to tradable assets. Similarly, Lens Protocol, operating out of the United Kingdom, offers a decentralized social graph that allows creators to own their profiles and followers as NFTs, emphasizing portability and interoperability across applications.
Farcaster, headquartered in West Hollywood, provides another critical layer with its decentralized social protocol featuring NFT-based identities and collectibles. The platform has recently seen significant corporate activity, including an acquisition by Neynar in early 2026, which signaled a strategic shift toward developer-focused tools for on-chain social features. Zora, based in New York, continues to expand its on-chain social network and NFT protocol, recently launching Attention Markets on Solana in February 2026. This move allows users to trade social trends and cultural moments, further blurring the lines between content consumption and financial speculation.
Beyond the major protocols, specialized entities are carving out niches. BLAQclouds, Inc., located in Robesonia, Pennsylvania, provides the ApolloNFT Marketplace and theAlley SocialFi platform, recently expanding their offerings in March 2026 to enhance NFT minting and direct fan monetization capabilities. CyberConnect, with primary operations in Singapore, focuses on the social identity layer, using NFTs for user profiles and connections. Cheelee, also based in Singapore, targets the short-video segment with NFT glasses that enable reward earning and content monetization. These companies illustrate the diversity of approaches within the market, ranging from infrastructure layers to consumer-facing applications.
Recent developments highlight the velocity of change. The acquisition of Farcaster by Neynar suggests a consolidation trend where infrastructure providers seek to control the social stack. Zora's expansion into attention markets indicates a pivot toward monetizing cultural relevance directly on-chain. Meanwhile, BLAQclouds' platform updates emphasize the ongoing demand for tools that simplify creator monetization. These events collectively point to a market that is rapidly maturing, with companies increasingly focusing on sustainability, developer tooling, and tangible revenue generation rather than pure user acquisition.
SocialFi NFTs Market
Industry Dynamics and Adoption Signals
Several key dynamics are currently shaping the operational environment for SocialFi NFTs. Market growth remains robust, with independent analyst insights estimating the sector's scale in the hundreds of millions, driven largely by the dominance of Social Content Monetization NFTs. The United States, in particular, is projected to experience significant growth rates, fueled by platforms like Friend.tech and a mature creator economy. However, global adoption is evident, with protocols recording millions of daily active wallets in early 2026. This level of engagement indicates that users are moving beyond testing phases into habitual usage of decentralized social tools.
Monetization capabilities are proving to be a key retention driver. Reports indicate that top creators on platforms like Lens have generated substantial income through collect NFT sales and tipping mechanisms in the first quarter of 2026. These figures demonstrate that the economic value proposition of SocialFi is becoming real for participants, not just theoretical. For businesses, this signals a shift in value capture strategies. Platforms that can facilitate seamless monetization while maintaining user experience standards are likely to capture more value than those relying solely on advertising or speculative tokenomics.
Nevertheless, the noise of industry data requires careful filtering. While overall growth is positive, specific segments may vary in performance based on macroeconomic conditions and regulatory developments. The presence of multiple competing standards and the evolving nature of blockchain scalability solutions add layers of complexity to strategic planning. Organizations must remain agile, monitoring not just price action but also user retention metrics, governance participation rates, and the integration of social NFTs with broader Web2 platforms.
What This Report Delivers for Enterprise Decision-Makers
Our comprehensive report, "SocialFi NFTs Market," is designed to provide the depth required for high-stakes decision-making. It goes beyond surface-level summaries to offer an executive summary that distills key findings for C-suite consumption. The methodology section details the research approach, ensuring transparency and reliability for stakeholders who need to validate the data for internal governance or investment committees.
The core of the report includes a rigorous market estimate analysis covering the historical period from 2020 to 2025 and a detailed forecast extending to 2032. This analysis breaks down the market by region, allowing strategists to identify high-potential geographies without relying on generalizations. It also segments the market by type and application, providing the specific revenue values and growth rates necessary to size opportunities accurately. For example, knowing the exact market size of Creator Monetization NFTs versus Membership Passes enables targeted product development and resource allocation.
Additionally, the report features a vendor analysis section profiling key companies in detail, including their product offerings, recent developments, and strategic positioning. This section is invaluable for competitive intelligence, partnership identification, and M&A targeting. It contextualizes recent moves, such as platform expansions and acquisitions, within the broader market trajectory. The report also addresses market dynamics, exploring drivers, restraints, and trends that will influence the sector's evolution. For organizations looking to enter the market, the segmentation analysis provides a roadmap of where value is being created and where gaps remain.
Ultimately, this research serves as a strategic compass. Whether you are a technology provider building the next social layer, an investor evaluating exposure to the creator economy, or a brand exploring NFT-based loyalty programs, the data within this report is structured to support evidence-based strategy. The full document contains the precise figures and detailed breakdowns necessary to build financial models and market entry plans.
Accessing the Full Intelligence
The landscape of SocialFi NFTs is complex, dynamic, and rapidly evolving. While this overview highlights the strategic importance of the market, the actionable intelligence required to navigate it lies in the details. The interplay of specific regional growth rates, exact revenue splits across types and applications, and deep-dive company profiles necessitates a comprehensive view that only the full report can provide.
We invite industry leaders, analysts, and strategic planners to access the complete SocialFi NFTs Market report. By doing so, you will gain access to the granular data, forecasts, and competitive analyses needed to make informed decisions in 2026 and beyond. In a market defined by speed and innovation, having access to verified, detailed intelligence is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: SocialFi NFTs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global All Solid State RF Power Supply Market to Hit $2.76B by 2032 at 9.48% CAGR
By pmarketresearch, 2026-09-16
Powering the Next Decade: Strategic Insights into the Worldwide All Solid State RF Power Supply Market
The global industrial landscape is undergoing a fundamental transformation in how energy is delivered, controlled, and optimized across critical manufacturing and scientific processes. At the forefront of this shift is the worldwide all solid state RF power supply market, a sector that has evolved from a niche technology provider into a cornerstone of modern plasma processing, industrial heating, and advanced semiconductor fabrication. As organizations navigate increasing demands for precision, energy efficiency, and operational reliability, understanding the strategic trajectory of this market has become indispensable for executive decision-making. This comprehensive analysis outlines the market structure, competitive dynamics, technological drivers, and forward-looking opportunities that will define the industry through the mid-2030s.
Recent historical performance demonstrates a steady, compounding expansion. Between 2020 and 2025, the market grew from approximately 912.45 million USD to 1465.0 million USD, reflecting a consistent upward trajectory fueled by the gradual replacement of legacy vacuum tube and magnetron-based systems. Looking ahead, the forecast period spanning 2026 to 2032 projects a robust compound annual growth rate of 9.48 percent. By the close of the forecast horizon, the market is anticipated to reach 2765.26 million USD in revenue. These figures are not merely statistical milestones; they represent a structural realignment in how industries source, regulate, and deploy radio frequency energy. For corporate strategists, capital allocators, and technology procurement leaders, this growth trajectory signals both immediate deployment opportunities and long-term value creation pathways.
Foundational Market Architecture and Strategic Segmentation
The revenue distribution across the global all solid state RF power supply market reveals distinct concentration patterns that directly inform sourcing strategies, partnership models, and regional investment prioritization. Historically, the Asia Pacific region has commanded the largest share of total market revenue, followed by North America and Europe. The Rest of World segment, while comparatively smaller in absolute terms, is experiencing accelerated adoption as emerging industrial hubs and specialized research facilities integrate solid state RF solutions into localized production ecosystems. Understanding these geographic weight distributions is critical for companies evaluating supply chain resilience, localized service infrastructure, and market entry sequencing.
Power output segmentation further illuminates the operational priorities driving procurement decisions. The 2 kW to 5 kW bracket consistently represents the highest revenue concentration, underscoring the widespread demand for mid-range precision power delivery across semiconductor processing, thin film manufacturing, and controlled plasma applications. The below 2 kW segment holds significant volume in specialized laboratory, medical, and low-power industrial use cases, while the above 5 kW category captures high-intensity industrial heating, large-scale plasma excitation, and next-generation fusion research environments. Revenue distribution across these power tiers highlights how manufacturers balance throughput requirements against thermal management, cooling architecture, and control system complexity.
Application-driven segmentation reveals where the technology is creating the most measurable operational impact. Semiconductor etching continues to represent a dominant demand driver, reflecting the industry's relentless push toward finer feature dimensions, higher process repeatability, and tighter plasma uniformity tolerances. Thin film deposition follows as a closely aligned growth pillar, where precise RF energy modulation directly influences film quality, adhesion, and material stoichiometry. Medical treatment and imaging applications contribute a substantial and steadily expanding revenue stream, leveraging solid state RF for controlled therapeutic heating, diagnostic equipment, and non-invasive procedural technologies. Industrial plasma applications round out the core demand base, supporting surface treatment, cleaning, activation, and specialized material processing across aerospace, automotive, and advanced manufacturing verticals.
Technological Catalysts and Regulatory Alignment
The accelerated transition toward all solid state RF power architecture is fundamentally rooted in performance economics rather than incremental upgrades. Solid state designs rely on advanced semiconductor devices such as LDMOS, GaN, and SiC transistors as core amplification components, enabling high-efficiency power conversion with dramatically improved thermal stability and modulation responsiveness. The operational advantages are quantifiable: modern solid state RF power supplies routinely achieve energy efficiencies ranging from 60 to 95 percent, and in continuous industrial processes, this performance differential can reduce energy expenditures by as much as 50 percent when compared to traditional tube-based architectures.
Beyond efficiency, the industry is propelled by the demand for longer operational lifetimes, precise digital control, and substantially reduced maintenance overhead. Vacuum tube and magnetron systems inherently carry wear-related degradation, frequency drift, and periodic replacement burdens that disrupt high-uptime production environments. Solid state RF platforms address these vulnerabilities through modular design, real-time impedance management, and software-defined power profiling. These capabilities are increasingly non-negotiable in advanced manufacturing lines where process consistency directly correlates with yield, scrap reduction, and capital equipment utilization.
Regulatory alignment further reinforces market momentum. Operation within designated ISM frequency bands such as 13.56 MHz, 27.12 MHz, and 2.45 GHz enables manufacturers to maintain compliance for industrial, scientific, and medical RF power applications while maintaining controlled electromagnetic emissions. This regulatory compatibility streamlines global sourcing, simplifies certification pathways, and reduces integration friction across multinational production facilities. For enterprises scaling operations across jurisdictions, ISM band alignment is not a technical footnote; it is a strategic enabler of deployment velocity.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively accounting for approximately 54.2 percent of total industry revenue, while the top five firms command an estimated 68.85 percent. This concentration indicates a mature yet still dynamic competitive environment, where scale advantages, application-specific engineering capabilities, and integrated delivery ecosystems play decisive roles in customer acquisition and retention. The presence of strong regional specialists alongside global technology incumbents creates a multi-layered procurement landscape that rewards buyers who align vendor capabilities with process requirements rather than defaulting to generalized brand recognition.
Solid State Power Amplifiers Market
Advanced Energy continues to anchor its market presence through solid state RF plasma generators such as the eVerest, Paramount Plus, and Paramount series, which deliver precise RF and pulse control tailored for plasma processing and semiconductor applications. Their product philosophy emphasizes control fidelity and process repeatability, positioning the company as a preferred partner for high-stakes fabrication environments.
MKS Instruments maintains a differentiated value proposition by delivering solid state RF power generators integrated with impedance matching networks, effectively offering a complete RF delivery system rather than isolated power components. This systems-level approach resonates strongly with thin film processing equipment manufacturers seeking to reduce integration complexity, streamline troubleshooting, and improve overall plasma stability.
Worldwide All Solid State RF Power Supply Market
TRUMPF Hüttinger strengthens the European industrial supply base through its TruPlasma RF and MW series, which support plasma excitation and industrial heating applications. Their engineering heritage and cross-sector industrial footprint provide credible continuity for customers operating in demanding thermal and plasma environments.
Coaxial Power Systems Ltd addresses cost-sensitive and highly customized industrial use cases by specializing in solid state RF power supplies and automatic matching networks for sputter coating, inductively coupled plasma, diamond deposition, plastic welding, and bespoke scientific projects. Their flexible engineering model is particularly relevant for laboratories and specialized manufacturers requiring tailored RF configurations without excessive lead times.
Elite RF LLC pushes into the high-power segment with solid state RF amplifiers and microwave generators reaching up to 100 kW, marketed explicitly as replacements for magnetrons in plasma generation, CVD diamond growth, and precision industrial heating. Their capability to substitute legacy microwave sources while retaining or improving process outcomes positions them as a strategic alternative for facilities seeking to retire aging tube infrastructure.
Empower RF Systems supplies technologically advanced high-power solid state RF and microwave amplifiers and systems, available in both air-cooled and liquid-cooled configurations, serving industrial, test and measurement, and defense-related RF power applications. Their emphasis on cooling architecture flexibility and high-power system integration broadens their addressable market across both commercial and specialized government-adjacent use cases.
Aethera Technologies develops high-efficiency APG series solid state RF generators spanning 10 to 400 kW, targeting industrial heating, plasma, and fusion research applications with a reliability-first mindset that explicitly contrasts against vacuum tube technology. Their stated efficiency ceiling approaching 95 percent reinforces the broader industry narrative that energy performance and uptime reliability can be optimized simultaneously.
pinkRF B.V. has emerged as a notable innovator in programmable solid state RF energy generation, recently introducing the MPG10kS 10 kW model for 2.45 GHz ISM band applications. The product highlights improved reliability, precision control, and longevity over magnetron systems for plasma and industrial heating. The company amplified visibility through a trade show exhibition at SEMICON Europa 2025, positioning the platform as a magnetron alternative with measurable efficiency and control advantages.
Crescend Technologies continues to pioneer solid state RF microwave generators and systems as magnetron alternatives for material processing, mining, and laboratory applications, with an emphasis on zero emissions outcomes. This environmental and operational positioning appeals to organizations seeking cleaner process footprints alongside dependable microwave energy delivery.
Ampegon contributes a specialized but strategically important capability through fully solid state RF amplifiers built on modular LDMOS technology, supporting CW or pulsed outputs for accelerator and scientific applications across frequencies from 120 to 500 MHz and powers up to 320 kW CW. Their high-frequency, high-power design scope addresses demanding research and scientific infrastructure requirements that are less sensitive to volume pricing but highly sensitive to performance and reliability.
Recent activity from Wattsine Electronic Technology Co., Ltd. further illustrates the pace of product iteration across the competitive field. At SEMICON China, the company exhibited ESL and ESM series full digital solid state RF power supplies alongside solid state microwave remote plasma sources, emphasizing high stability for semiconductor applications. Such exhibition activity signals that digital control integration and remote plasma architecture are becoming standard competitive benchmarks rather than differentiating luxuries.
Operational Intelligence Embedded in the Research Framework
A strategically valuable market study must extend beyond top-line sizing and generic segmentation to provide actionable intelligence that procurement leaders, R&D directors, and corporate strategists can operationalize. The research framework associated with this market assessment is structured to support precisely that objective. It delivers a comprehensive mapping of historical demand patterns and forward-looking growth inflection points, enabling organizations to stress-test capacity planning, supplier diversification, and capital expenditure timing.
The analytical scope includes detailed segmentation evaluations that illuminate where revenue intensity is concentrated and where adoption curves are accelerating. By isolating power output requirements, application-specific consumption behaviors, and regional deployment momentum, the research equips decision-makers to align product roadmaps, distribution strategies, and service infrastructure investments with the highest-probability demand nodes. The inclusion of concentration metrics further supports competitive benchmarking by clarifying the share dynamics that shape pricing leverage, partnership feasibility, and barrier-to-entry assessments.
In addition to structural segmentation, the research integrates technology transition indicators that explain why certain procurement cycles are shifting. The documented move toward high-efficiency solid state architectures, digital control interfaces, and modular amplifier designs is presented in a manner that connects engineering characteristics with commercial outcomes. This is critical for organizations evaluating total cost of ownership, maintenance scheduling, and facility upgrade sequencing. Rather than treating technology migration as an abstract trend, the research framework ties it to tangible operational advantages, including reduced downtime exposure, improved process repeatability, and lower long-term energy intensity.
Regulatory and standards alignment is also interwoven into the analysis, ensuring that market evaluation reflects real-world deployment constraints. Frequency band compatibility, electromagnetic emission control, and industrial compliance pathways are treated as strategic variables that influence product selection, cross-border procurement, and integration timelines. For enterprises managing multi-site operations or expanding into new regulatory environments, this dimension of the research provides a pragmatic lens for de-risking adoption decisions.
The competitive profiling embedded within the study goes beyond descriptive company summaries. It evaluates how major players structure their value propositions, where they concentrate engineering resources, and how recent product introductions or exhibition activity signal near-term market intent. By connecting product launches, trade show positioning, and application-specific messaging to broader commercial strategies, the research helps readers interpret competitor behavior as forward-looking signals rather than isolated announcements. This is particularly relevant for organizations tracking magnetron replacement pathways, high-power amplifier expansion, and digital control standardization, all of which are actively reshaping procurement expectations.
Strategic Implications for 2026 Decision-Making
For organizations preparing for 2026 and beyond, the worldwide all solid state RF power supply market presents a convergence of operational necessity and strategic opportunity. The combination of sustained growth momentum, measurable efficiency advantages, and accelerating technology migration creates a window in which procurement strategy, vendor evaluation, and internal capability development can be synchronized with long-term production goals. Companies that delay assessment risk paying a premium in energy cost, maintenance exposure, and process variability, particularly as competitors adopt solid state RF platforms that improve repeatability and reduce lifecycle friction.
Procurement and engineering leaders should treat the current market phase as an opportunity to recalibrate supplier partnerships. Concentration metrics suggest that scale players hold meaningful share, but specialized firms continue to capture high-value segments through application-specific design, flexible cooling architectures, and programmable control features. Evaluating vendors against actual process requirements, not just catalog specifications, will increasingly separate efficient adopters from organizations that overpay for misaligned capabilities.
Similarly, the push toward digital control, modular amplification, and ISM band compatibility indicates that future operational resilience will depend on integration readiness as much as raw power output. Facilities that plan for impedance management, thermal architecture, and software-defined tuning now will be better positioned to scale throughput without incurring disruptive retrofits later. For R&D-intensive organizations, the availability of high-power solid state alternatives to magnetrons and vacuum tubes opens new experimental and production pathways in plasma generation, material deposition, and precision heating.
Capital allocation decisions should also account for the energy economics embedded in solid state RF adoption. With efficiency improvements capable of substantially reducing operating costs in continuous industrial processes, the total cost of ownership calculus is shifting in favor of upfront integration investment where uptime, control precision, and energy savings compound over time. Decision-makers who model these trade-offs explicitly will gain a clearer line of sight into payback horizons, capacity utilization targets, and competitive cost positioning.
Path Forward: Accessing the Complete Intelligence Framework
The trajectory of the worldwide all solid state RF power supply market reflects more than incremental technological replacement; it signals a structural recalibration of how industry delivers, controls, and harvests RF energy across high-value applications. The market's growth arc, competitive concentration, and technology transition patterns all point toward an environment where informed strategic planning will separate scalable operators from reactive followers. For executives and technical leaders looking to translate this environment into concrete action, the full research study provides the detailed segmentation evidence, competitive profiling, and forward-looking scenario analysis required to support confident planning.
Readers seeking the complete dataset, in-depth regional and application breakdowns, competitive benchmarking detail, and comprehensive technology transition analysis are encouraged to access the full Worldwide All Solid State RF Power Supply Market research report directly. The complete study offers the granular intelligence necessary to convert high-level market awareness into targeted procurement strategy, investment prioritization, and operational roadmap development. In a market defined by efficiency imperatives, control precision, and accelerating solid state adoption, the depth of intelligence accessed today will shape the resilience and competitiveness of industrial decisions throughout the coming forecast cycle.
For detailed analysis of this topic, please visit the official page: Worldwide All Solid State RF Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Laser Type Oil Film Detector Market to Hit $191.2M by 2032, Expanding at 6.32% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Worldwide Laser Type Oil Film Detector Market 2026-2032
In an era where environmental compliance and industrial safety intersect with technological precision, the global market for laser type oil film detectors is undergoing a significant transformation. PW Consulting is proud to release our comprehensive Worldwide Laser Type Oil Film Detector Market research, a definitive guide designed to empower corporate strategists, procurement leaders, and investment analysts with actionable intelligence for the 2026 fiscal year and beyond. As industries face mounting pressure to monitor hydrocarbon contamination in real-time, understanding the trajectory of this specialized instrumentation market is no longer optional—it is a strategic imperative.
Worldwide Vibration Detector Market
This market research serves as a critical roadmap for navigating the complexities of industrial environmental monitoring. By integrating historical performance data from 2020 through 2025 with a forward-looking forecast extending to 2032, our analysis provides a robust framework for decision-making. The report is structured to reveal not just where the market stands today, but how it will evolve under the influence of regulatory shifts, technological advancements, and regional industrial growth. For executives aiming to secure market share or optimize supply chain investments, this document offers the granularity required to move from assumption to certainty.
Global Market Trajectory and Financial Outlook
The financial architecture of the laser type oil film detector market demonstrates resilient growth, driven by the dual forces of stricter environmental legislation and the modernization of industrial sensing infrastructure. Based on our comprehensive analysis, the global market generated revenue of 124.5 million USD in the base year of 2025. This figure represents the culmination of a steady growth period observed from 2020 to 2025, reflecting the increasing adoption of non-contact optical sensing technologies over traditional manual inspection methods.
Worldwide Laser Type Oil Film Detector Market
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion trajectory. The market is anticipated to reach a valuation of 132.37 million USD in 2026, growing consistently to exceed 191.2 million USD by 2032. This growth path underscores a Compound Annual Growth Rate (CAGR) of 6.32 percent over the forecast horizon. Such a rate indicates a healthy, sustained demand rather than a temporary spike, suggesting that investment in this sector offers long-term stability. The consistent year-over-year increase highlights the deepening integration of laser-based detection systems into standard operational protocols across heavy industry and energy sectors.
This financial outlook is not merely a projection of unit sales but a reflection of value addition. As detectors become more sophisticated, incorporating features like false alarm prevention and extended operational ranges, the average value per unit is expected to support the revenue growth even as volume scales. For stakeholders, this means that the market opportunity is not solely dependent on mass adoption but also on the premiumization of technology capable of meeting rigorous industrial standards.
Segmentation Dynamics and Application Drivers
Our research delves deep into the structural components of the market, dissecting the demand across product types and end-use applications. This segmentation is vital for companies looking to specialize their product portfolios or identify underserved niches. The market is currently defined by a diverse range of hardware solutions, with a notable concentration in scanning technologies that offer comprehensive coverage of water surfaces and industrial drainage systems. Fixed-point sensors and portable units also constitute significant portions of the product landscape, catering to specific monitoring needs where mobility or continuous stationary surveillance is required.
The application landscape reveals where the critical demand originates. Oil and gas refineries remain a primary driver, necessitating robust monitoring to prevent hydrocarbon discharge into drainage and storage facilities. Marine and offshore platforms represent another substantial vertical, where the detection of oil films on water is crucial for both environmental compliance and operational safety. Power generation plants and industrial wastewater management facilities also contribute significantly to the demand profile, leveraging laser technology to ensure that effluent discharge meets stringent regulatory limits.
Geographically, the market exhibits a distinct distribution of demand. Asia Pacific stands as the largest regional contributor, reflecting the intense industrial activity and manufacturing output in the region. Europe follows as a significant market, driven by rigorous EU environmental directives and a mature industrial base. North America maintains a strong presence, supported by its extensive energy infrastructure and stringent safety regulations. Meanwhile, emerging opportunities are being tracked in the Middle East and Africa, as well as Latin America, where industrial expansion is beginning to necessitate advanced monitoring solutions. Our report provides detailed analysis of these regional variances without exposing the specific allocation percentages, directing stakeholders to the full dataset for precise regional planning.
Competitive Landscape and Strategic Player Analysis
The market environment is characterized by a mix of established Japanese manufacturers dominating the technology space and innovative players entering from other regions. The competitive landscape is moderately concentrated, with the top three companies holding a combined market share that reflects the high barrier to entry regarding specialized laser technology and certification standards. The top five players collectively command a significant portion of the market, indicating that partnerships or acquisitions with these key entities could be a viable strategy for broader market access.
Asahi Kasei Technosystem, headquartered in Japan, continues to be a pivotal player with its Apolarm series, including the LMD-3000N and LMD-600 models. These products are renowned for their ability to detect micron-level films at specific distances, making them essential for environmental monitoring in drainage and purification plants. Competitor HORIBA Ltd. also maintains a strong position with its LO-300 laser scanning oil film detector, which utilizes semiconductor laser technology for non-contact detection. HORIBA's focus on extended laser module life and improved resistance to false alarms from debris demonstrates a commitment to reliability in harsh industrial environments. DKK-TOA Corporation and TOKYO KEIKI INC. further strengthen the Japanese presence in the market, offering both explosion-proof and non-explosion-proof variants suitable for diverse safety requirements in industrial settings.
On the international front, Laser Diagnostic Instruments AS (LDI) from Estonia provides a unique value proposition with its ROW remote optical watcher technology. Capable of detecting oil films from significant heights, LDI addresses applications where access to the water surface is limited, expanding the utility of laser detection in offshore and large-scale environmental monitoring. The presence of these key companies creates a dynamic competitive environment where differentiation through specification, certification, and regional support becomes the primary battleground.
Regulatory Tailwinds and Technological Innovations
Market dynamics are heavily influenced by the regulatory environment. In key jurisdictions, revisions to safety acts and environmental compliance standards are mandating earlier detection of oil leaks in industrial drainage and storage facilities. For instance, in Japan, laser type oil film detectors are increasingly recognized as supports for compliance with the Fire Service Act revisions. This regulatory pressure transforms the detector from a optional safety tool into a required compliance asset, directly stimulating market demand.
Technological specifications are evolving to meet these regulatory needs. Recent industry developments highlight a focus on durability and accuracy. For example, recent product demonstrations by HSA Asia and Asahi Kasei in early 2026 showcased comprehensive performance testing of the Apolarm M LMD-3000, emphasizing its capability in thin-layer detection within drainage systems. Such events validate the technology for procurement teams and signal a market readiness to adopt higher-specification units. Furthermore, advancements such as extended laser module life and certifications like CE marking compliant with EMC and Low-voltage Directives are becoming table stakes for suppliers aiming to operate in global markets. These certifications ensure that equipment can be deployed safely in industrial environments without electromagnetic interference issues, a critical factor for plant managers.
The industry is also seeing a shift towards enhanced wave resistance and false alarm prevention. As detectors are deployed on flowing water surfaces or in areas with biological matter, the ability to distinguish between an oil film and debris is paramount. Manufacturers are responding by refining their optical algorithms and hardware resilience, ensuring that the data provided to operators is reliable enough to trigger immediate action without unnecessary downtime caused by false positives.
Strategic Value for 2026 Decision Making
For corporations operating in or servicing the industrial sector, the insights contained in this report are designed to mitigate risk and identify opportunity. The 2026 decision-making landscape requires a clear understanding of where capital should be allocated. Whether a company is looking to manufacture components, distribute finished units, or implement monitoring systems within their own facilities, the granular data on market size, growth rates, and competitive positioning is indispensable.
The report offers actionable content that goes beyond high-level summaries. It includes detailed profiles that assess the capabilities and strategic directions of key manufacturers, allowing readers to benchmark their own offerings or potential partners against industry leaders. By understanding the specific strengths of competitors—such as HORIBA's certification standards or Asahi Kasei's drainage system focus—businesses can carve out differentiated positions in the market. Additionally, the analysis of recent developments provides a pulse on the current pace of commercialization and technology validation, helping planners align their product launch timelines with market readiness.
Investment in this market is not just about selling hardware; it is about enabling compliance and safety. The report elucidates how the intersection of regulatory demand and technological capability creates a locked-in growth path. For investors, this reduces the uncertainty associated with technology adoption cycles. For vendors, it highlights the importance of aligning marketing and sales efforts with regulatory milestones and specific application pain points, such as oil-water separation in refineries or environmental monitoring in wastewater plants.
Conclusion and Access to Comprehensive Intelligence
The Worldwide Laser Type Oil Film Detector Market is at a pivotal stage where technology, regulation, and industrial necessity converge. The projected growth from 124.5 million USD in 2025 to over 191.2 million USD by 2032 signals a robust environment for strategic engagement. However, mastering this market requires more than just top-line numbers. It demands an understanding of the nuanced segmentation splits, the specific competitive advantages of key players, and the regional regulatory frameworks that dictate deployment.
PW Consulting's full market research report provides the depth required to navigate this landscape confidently. We have outlined the macro trajectory and the key players in this overview, but the strategic edge lies in the details. The complete report offers exhaustive data tables, deep-dive regional analyses, and specific revenue splits across segments that are essential for precise forecasting and resource allocation. We invite stakeholders to access the full intelligence package to equip their organizations with the knowledge needed to lead in this evolving sector. In a market driven by precision and compliance, having the most accurate intelligence is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Laser Type Oil Film Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com